Sony: Built for the Long Game
Updated: Aug 22
Sony is a global leader in entertainment, gaming, music, and imaging technology. Known for its PlayStation ecosystem, world class music and film businesses, and market leading image sensors, the company combines valuable intellectual property with technological leadership and a diversified business model. With a growing mix of recurring revenue, continued investment in gaming, music, and image sensors, and a focus on improving capital efficiency, Sony aims to deliver sustainable long term growth. The question remains: Does this entertainment and technology leader deserve a spot in your portfolio?
This is not financial advice. I am not a financial advisor, and I publish these analyses to document my own research and share my thoughts with readers and followers. If you are considering investing in any of the companies or ideas discussed, you should always do your own research and, if necessary, consult a qualified financial professional. All investing involves risk, and you may lose some or all of the money you invest.
For full disclosure, I do not own shares in Sony at the time of writing this analysis. I publicly share my investment portfolio, including all of my current holdings and changes I make over time. If you are interested in seeing what I currently invest in and learning how you can follow or copy my portfolio, you can read more here.
The Business
Sony Group Corporation is a diversified Japanese conglomerate with a global presence across entertainment, technology, and financial services. The company operates through several core segments: Game & Network Services, which includes the PlayStation gaming ecosystem; Music, covering recorded music, music publishing, and visual media; Pictures, which handles film and TV production through studios like Columbia Pictures and platforms such as Crunchyroll; Entertainment, Technology & Services, responsible for TVs, audio devices, cameras, and mobile phones; and Imaging & Sensing Solutions, which leads the market in CMOS image sensors used in smartphones, cameras, and increasingly in automotive and industrial applications. Sony also operates a Financial Services segment, offering insurance and banking in Japan, though this business is currently undergoing a spin-off. Sony was founded in 1946 in Tokyo and has developed from a consumer electronics manufacturer into one of the world’s largest entertainment and technology companies. Following the partial spin-off of Sony Financial Group in October 2025, Sony is now more focused on entertainment, intellectual property, and technologies that support content creation. Sony no longer includes the financial services business in its financial statements, although it still owns 16.,4% of the company. Entertainment, intellectual property, and creation technology now account for approximately 67% of consolidated sales, reflecting how far the company has moved away from its historical dependence on televisions, audio systems, and other consumer electronics. Sony operates through five main business segments: Game & Network Services, Music, Pictures, Entertainment, Technology & Services, and Imaging & Sensing Solutions. These businesses initially appear very different, but they are connected by Sony’s ability to create, own, distribute, and monetize entertainment while supplying many of the technologies used to produce and experience it. The company reaches consumers through PlayStation, music streaming, films, television, anime, cameras, headphones, and other premium electronics. It also serves business customers such as game developers, streaming platforms, filmmakers, broadcasters, smartphone manufacturers, and automotive companies. This combination makes Sony both a consumer-facing entertainment company and an important technology supplier to other global businesses. Game & Network Services is Sony’s largest business and includes the PlayStation ecosystem. Sony develops and sells PlayStation consoles, controllers, accessories, games, downloadable content, and network services. The company earns revenue when customers purchase hardware and games, but an increasing proportion comes from digital transactions and recurring services. Third-party developers distribute games and additional content through the PlayStation Store, with Sony receiving a share of each transaction. Players can also subscribe to PlayStation Plus, which provides online multiplayer access, cloud storage, discounts, and access to libraries of games. This means that PlayStation is no longer simply a console sold every several years. It is a continuously operating digital platform through which Sony maintains a direct relationship with players and earns revenue throughout the console’s life. Sony also owns a portfolio of game development studios and franchises, including God of War, Gran Turismo, Horizon, Ghost of Tsushima, The Last of Us, and Uncharted. Through licensing arrangements, Sony’s game portfolio also includes highly valuable titles based on characters such as Spider-Man. These games help attract players to PlayStation, differentiate the platform from competing consoles, and generate software sales with better economics than the hardware itself. Sony is also expanding selected PlayStation franchises into personal computer games, mobile entertainment, television series, and films, allowing the company to reach audiences beyond PlayStation consoles. The PlayStation platform had a record 125 million monthly active users in March 2026, while cumulative PlayStation 5 sales had exceeded 93 million units. Sony’s Music segment consists primarily of recorded music, music publishing, artist services, merchandising, and anime-related activities. Sony Music Entertainment works with artists and distributes recorded music through labels such as Columbia Records, RCA Records, and Epic Records. The company earns revenue when music is streamed through services such as Spotify, Apple Music, and YouTube, as well as from physical music sales, merchandise, live performances, and licensing music for advertisements, films, television programs, and games. Sony also owns The Orchard and AWAL, which provide distribution and support services to independent artists and record labels. Sony Music Publishing owns or administers the rights to an extensive catalog of musical compositions. Unlike recorded music rights, which relate to a specific recording of a song, publishing rights relate to the underlying lyrics and composition. Sony receives royalties whenever these compositions are streamed, performed, broadcast, reproduced, or licensed for other media. Because successful songs can continue to generate royalties for decades and can be monetized repeatedly across countries and formats, music publishing provides Sony with relatively predictable and recurring revenue. Sony’s music operations also benefit from a global presence and the ability to discover and develop local artists across markets such as Japan, India, Brazil, Africa, Europe, and North America. Digital streaming has made it easier to distribute this content globally without requiring Sony to manufacture or transport physical products, improving the scalability of the business. Sony’s Pictures segment produces, acquires, and distributes films and television programs through operations including Columbia Pictures, TriStar Pictures, Screen Gems, Sony Pictures Animation, and Sony Pictures Television. Its portfolio includes franchises and properties such as Spider-Man, Jumanji, Bad Boys, and Ghostbusters, together with a large library of films, television series, game shows, and other programming. Sony can monetize this content through cinemas, digital purchases, video-on-demand services, television networks, home entertainment, and licensing agreements with streaming platforms. Unlike several competing studios, Sony does not operate a large general entertainment streaming service in most Western markets. Instead, it frequently licenses films and television programs to companies such as Netflix and Amazon. This strategy allows Sony to receive content licensing revenue without bearing the full cost of competing directly in the increasingly crowded general streaming market. Sony has, however, established a strong direct-to-consumer position within anime through Crunchyroll. The service provides anime streaming, theatrical distribution, mobile games, merchandise, events, and other services to anime fans around the world. Crunchyroll surpassed 21 million paid subscribers by the end of March 2026 and distributes more than 50,000 episodes with subtitles or dubbing in more than 13 languages. Sony’s position in anime extends beyond distribution. Through Aniplex and related studios, it participates in the development, production, financing, licensing, and merchandising of anime content. This gives Sony exposure to several parts of the anime value chain, from identifying and producing promising intellectual property to distributing it internationally through Crunchyroll. The company can then generate additional revenue from cinema releases, games, music, merchandise, and licensing. Sony is strengthening this ecosystem through closer collaboration between Aniplex, Crunchyroll, PlayStation, and Sony Music, as well as through partnerships with Japanese publishers and content owners. The Entertainment, Technology & Services segment contains many of the products traditionally associated with Sony, including Alpha cameras and lenses, professional imaging equipment, headphones, wireless speakers, smartphones, projectors, televisions, home audio systems, and technology used by broadcasters and content producers. Rather than competing primarily through low prices or mass-market volume, Sony has increasingly concentrated on premium products where its brand, engineering expertise, image quality, sound quality, and relationships with professional creators provide differentiation. The Alpha camera system has established Sony as an important supplier to photographers, filmmakers, online creators, and broadcasters. The company also sells professional equipment and services used in film production, sports broadcasting, virtual production, medical imaging, and content creation. This segment therefore supports Sony’s broader entertainment strategy by supplying some of the tools used to create and consume content. Sony is further reducing its direct exposure to commoditized hardware manufacturing. In March 2026, it signed definitive agreements with TCL to establish a home entertainment joint venture covering Bravia televisions, business displays, home theatre products, and home audio equipment. TCL is expected to own 51% of the venture and Sony 49%, combining Sony’s brand and audio-visual technology with TCL’s manufacturing scale, display technology, and supply chain. The planned structure should allow Sony to retain exposure to its premium brand and technology while reducing the capital requirements and operational risks associated with competing in mature hardware categories. Imaging & Sensing Solutions develops and manufactures CMOS image sensors and related semiconductor products. These sensors convert light into digital information and are essential components in smartphone cameras, digital cameras, security systems, industrial equipment, and vehicles. Sony is the global leader in image sensors by revenue, with its share estimated at approximately 56% for calendar year 2025. The business is particularly strong in premium smartphone sensors, where customers require high image quality, rapid processing, strong low-light performance, accurate focusing, and increasingly sophisticated computational photography. Sony works closely with major smartphone manufacturers to develop customized sensors for upcoming devices, often becoming involved years before a product reaches the market. The company is also investing in automotive sensors used by advanced driver-assistance systems to detect vehicles, pedestrians, road markings, and other objects. Industrial automation, security cameras, and content creation provide additional long-term applications. Sony’s competitive moat is built on its valuable intellectual property, platform ecosystems, technological leadership, production and distribution scale, relationships with creators and business customers, and the ability to connect these advantages across several forms of entertainment. The most important element of the moat is Sony’s ownership and control of content. Its games, music catalogs, films, television programs, and anime properties can be monetized repeatedly across different formats, platforms, countries, and generations. A successful game can generate revenue from the initial sale, downloadable content, subscriptions, merchandise, licensing, personal computer releases, and adaptations into television or film. A successful song can generate royalties whenever it is streamed, broadcast, performed, or included in other media. A film or television series can earn revenue through cinemas, digital distribution, television licensing, streaming agreements, and future remakes or spin-offs. This ability to monetize the same intellectual property repeatedly gives Sony more durable economics than a traditional hardware company that must continually persuade consumers to purchase newly manufactured products. The size and diversity of Sony’s intellectual property portfolio also reduce its dependence on any single release. Individual games, films, and artists can perform unpredictably, but Sony owns and manages thousands of entertainment assets across different genres, markets, and formats. Older catalogs continue generating revenue while newly developed intellectual property creates future growth opportunities. Building a comparable portfolio would require competitors to spend many years developing content, acquiring rights, establishing relationships with creators, and building international distribution capabilities. The PlayStation ecosystem represents another major competitive advantage. Players accumulate digital game libraries, saved progress, trophies, subscriptions, online identities, and social relationships on the platform. Moving to another console may therefore require giving up access to purchased games or rebuilding parts of the user’s digital and social experience. These switching costs are especially meaningful for groups of friends who play multiplayer games together and must generally use compatible platforms. The large installed base also attracts game developers because it provides access to a substantial audience. A broad range of games makes PlayStation more attractive to consumers, while the growing player base makes it more attractive to developers. This creates a network effect that reinforces the platform over time. Sony benefits financially from this ecosystem even when it does not develop the game itself because it receives platform fees from third-party software and digital content sold through the PlayStation Store. The migration from physical games toward digital downloads, subscriptions, and add-on content deepens the customer relationship and increases the amount of revenue generated after the original console purchase. Sony’s first-party studios strengthen this ecosystem by developing differentiated games that attract users and reinforce PlayStation’s brand. However, the moat does not depend solely on exclusive titles. It also rests on the scale of the network, the breadth of third-party content, the established developer community, the global distribution system, and the digital libraries already owned by users. Sony’s music businesses benefit from similar scale advantages. Streaming services need access to broad music catalogs, while artists and songwriters benefit from working with companies that can provide global promotion, distribution, data, financing, and licensing opportunities. Sony’s size allows it to negotiate with digital platforms, invest in artist development, operate across many countries, and distribute the cost of technology and administration across a large catalog. The catalog itself is difficult to reproduce because the rights to successful songs are scarce and often remain commercially valuable for decades. Sony’s publishing operations receive royalties across a wide range of platforms and uses, creating recurring revenue without requiring the company to recreate the underlying composition each time it is consumed. Sony’s growing anime ecosystem provides another attractive competitive position. Crunchyroll’s scale gives Sony direct access to millions of highly engaged anime fans around the world, along with data about viewing preferences and demand. This makes the platform valuable to Japanese studios and publishers that want to reach international audiences. At the same time, access to a large and differentiated content library makes Crunchyroll more valuable to subscribers. Sony can support an anime title through financing, production, music, theatrical distribution, streaming, games, merchandise, and international marketing. Few competitors possess comparable capabilities across so much of the anime value chain. This does not mean that Sony owns every title available through Crunchyroll, but its distribution scale and relationships with content owners strengthen its position when competing for licensing and collaboration opportunities. Technological expertise provides another layer of protection, particularly within image sensors. Sony has spent decades developing semiconductor design, manufacturing processes, pixel technology, image processing, and relationships with leading device manufacturers. Smartphone companies cannot easily replace a critical image sensor purely on the basis of price because camera performance is an important selling point for premium devices and the sensor must be integrated with lenses, processors, software, and the physical design of the phone. Qualification and product development take time, creating close and relatively durable relationships between Sony and its customers. The enormous cost of building fabrication capacity, developing competitive sensor technology, and achieving acceptable manufacturing yields creates a substantial barrier to entry. Sony’s leading market share also provides economies of scale that allow it to invest more heavily in research and production than smaller competitors. The company’s experience in cameras, professional imaging, and consumer electronics further supports its understanding of how images are captured, processed, and displayed. Sony’s global brand also remains an important advantage. The brand has been built over decades and is associated with entertainment, innovation, image quality, sound quality, and premium technology. It provides credibility when Sony launches new products and helps the company maintain premium positioning in categories such as cameras, headphones, gaming, and professional equipment. Sony also has extensive global distribution, marketing, and customer support capabilities, together with long-standing relationships with retailers, creators, game developers, streaming platforms, smartphone manufacturers, broadcasters, and film distributors. These relationships would be difficult and expensive for a new competitor to establish at comparable scale. Perhaps Sony’s most distinctive advantage is its ability to combine content, technology, and distribution within the same group. PlayStation games can be adapted by Sony Pictures into films or television series, while Sony Music can contribute soundtracks and artist collaborations. Anime developed or financed through Aniplex can be distributed internationally through Crunchyroll, supported by Sony Music, and expanded into games and merchandise. Sony’s cameras, sensors, production tools, and professional technology can support the creators who produce this entertainment. Successful adaptations such as The Last of Us demonstrate how Sony can extend the life and audience of intellectual property beyond its original format. These collaborations do not guarantee that every project will succeed, and Sony’s decentralized structure can sometimes make coordination difficult, but the underlying combination of assets is unusual and difficult for competitors to reproduce. Microsoft and Nintendo have strong gaming ecosystems, but neither has Sony’s position in music, film, anime, cameras, and image sensors. Disney owns exceptional entertainment franchises, but it does not operate a comparable gaming platform or semiconductor business. Music companies possess valuable catalogs but lack Sony’s direct access to gaming audiences and visual entertainment production. Semiconductor competitors may challenge Sony in image sensors, but they generally lack its relationships with creators and its broader understanding of imaging across both professional and consumer applications. Sony’s moat therefore does not come from one dominant product. It comes from several valuable and independently defensible businesses that are becoming increasingly connected. PlayStation provides a large digital platform and strong switching costs, music and film provide scarce intellectual property, Crunchyroll provides direct access to a growing global anime audience, and image sensors provide technological leadership in a highly demanding semiconductor category. Combined with Sony’s brand, financial resources, global distribution, and relationships with creators and customers, these advantages create a business ecosystem that would be extremely difficult for a new competitor to replicate. Sony’s continued shift away from lower-margin, commoditized hardware and toward entertainment, intellectual property, recurring digital revenue, and advanced imaging technology should further strengthen this competitive position over time.
Management
Hiroki Totoki serves as the CEO of Sony Group Corporation, a position he formally assumed in 2025 after previously serving as President, COO, and CFO of the company. Having spent nearly four decades at Sony, Hiroki Totoki has played a central role in shaping the company's transformation from a consumer electronics manufacturer into a global entertainment and technology leader. His appointment reflects Sony's continued focus on strengthening its entertainment ecosystem, expanding recurring revenue, and allocating capital toward businesses with attractive long-term growth opportunities. Hiroki Totoki joined Sony in 1987 and has held a wide range of senior leadership positions across the group's diverse operations. Before becoming CEO, Hiroki Totoki served as Chief Financial Officer, President, and Chief Operating Officer of Sony Group Corporation. Earlier in his career, Hiroki Totoki led Sony's mobile communications business during a challenging period, where he successfully improved profitability by restructuring operations and focusing the business on premium products. He also served as CEO of Sony's financial services business, giving him extensive experience across both Sony's consumer and financial operations. These leadership roles provided Hiroki Totoki with a deep understanding of Sony's highly diversified business model and the opportunities created by combining technology, entertainment, and intellectual property. As Chief Financial Officer, Hiroki Totoki became known for his disciplined approach to capital allocation and financial management. He strengthened Sony's balance sheet while directing investment toward areas where the company possesses durable competitive advantages, including PlayStation, image sensors, music, and entertainment intellectual property. Hiroki Totoki has consistently emphasized the importance of improving capital efficiency, maintaining financial discipline, and investing for long-term value creation rather than pursuing short-term earnings growth. During his tenure, Sony completed several important strategic transactions, including acquisitions that strengthened its content portfolio, the expansion of PlayStation Studios, and the spin-off of Sony Financial Group, allowing management to sharpen its focus on entertainment and technology while simplifying the group's structure. Hiroki Totoki has also been one of the principal architects of Sony's strategy to increase collaboration across its businesses. Rather than operating as independent divisions, Sony increasingly seeks to connect its gaming, music, film, anime, and technology operations to maximize the value of its intellectual property. Successful examples include adapting PlayStation franchises into television series and films, strengthening the anime ecosystem around Crunchyroll and Aniplex, and creating closer collaboration between Sony's content businesses and its technology platforms. Hiroki Totoki has described this approach as building value through bottom-up collaboration, where individual business units work together while maintaining the entrepreneurial culture that has helped make each business successful. Since becoming CEO, Hiroki Totoki has continued to refine Sony's strategic focus. The company has reduced its exposure to lower-margin hardware businesses while increasing investment in entertainment, intellectual property, image sensors, and creation technologies. Sony also entered into a strategic partnership with TCL to strengthen the competitiveness of its television and home entertainment business while allowing management to focus more resources on higher-growth areas. Under Hiroki Totoki's leadership, Sony continues to position itself as a company where premium technology, proprietary intellectual property, and digital platforms reinforce one another to create long-term shareholder value. Hiroki Totoki graduated from Keio University with a degree in economics. Throughout his career, Hiroki Totoki has built a reputation as a pragmatic, financially disciplined, and highly analytical leader who combines operational expertise with a long-term strategic perspective. Given his extensive experience across Sony's businesses and his role in shaping many of the company's most important strategic decisions over the past decade, Hiroki Totoki appears well positioned to guide Sony through its next phase of growth as the company continues expanding its entertainment ecosystem and technology leadership.
The Numbers
The first number we will look into is the return on invested capital, also known as ROIC. We want to see a 10-year history, with all numbers exceeding 10% in each year. Sony has generated solid, although not exceptional, returns on invested capital over the past decade. ROIC has exceeded 10% in four of the past ten years and remained close to that level in most of the others. While this falls short of what I ideally like to see, it is important to understand why Sony's returns are lower than those of many high-quality asset-light businesses. Sony operates one of the most diversified business models among large global companies. It combines highly profitable businesses such as PlayStation, Music, and image sensors with more capital-intensive operations such as image sensor manufacturing, consumer electronics, and film production. These businesses require significant ongoing investment in fabrication facilities, production equipment, studios, content creation, and technology, which naturally increases the amount of capital employed and reduces overall ROIC. One of the biggest factors is Sony's Imaging & Sensing Solutions business. The company is the global leader in CMOS image sensors and continues to invest heavily to maintain that position. Expanding image sensor production requires substantial investment in fabrication facilities and highly specialized equipment. These investments increase invested capital immediately, while the associated earnings often take several years to fully materialize. As a result, ROIC can temporarily decline during periods of heavy investment even though the underlying competitive position becomes stronger. Another factor is Sony Pictures. Management has acknowledged that the Pictures business currently generates an ROIC of around 6%, making it one of the group's lower-return businesses. Film and television production requires substantial upfront investment, projects often take years to complete, and financial returns can vary considerably from one release to another. Despite these lower returns, Sony Pictures remains strategically important because it owns valuable intellectual property and works closely with other parts of the group to extend franchises across games, television, film, anime, and music. Sony has also spent the past several years investing aggressively in areas such as PlayStation Studios, Crunchyroll, music catalogs, and semiconductor capacity. While these investments increase the company's capital base in the short term, management expects them to strengthen Sony's competitive position and support earnings growth over many years. The decline in ROIC between 2021 and 2025 therefore appears to be driven more by elevated investment levels and temporary margin pressure than by a deterioration in the underlying business. This is supported by the recovery to 10,9% in fiscal year 2026, suggesting that some of these investments are beginning to generate stronger returns. Improving capital efficiency has become an increasingly important priority under CEO Hiroki Totoki. Management has repeatedly stated that every business segment is measured on ROIC and that lower-return businesses are undergoing continuous structural improvements. Rather than simply trying to increase margins, Sony also aims to reduce capital intensity and investment risk where possible. The recently announced partnership with TCL for the television business is one example of this strategy, allowing Sony to maintain its premium brand and technology while reducing the capital required to compete in a mature hardware market. Likewise, the spin-off of Sony Financial Group allows management to focus more resources on entertainment, intellectual property, and advanced technologies where the company believes it can earn higher long-term returns. Looking ahead, I believe Sony's ROIC has the potential to improve gradually. The company is becoming increasingly focused on higher-margin businesses such as gaming, music, image sensors, and recurring digital services, while reducing its exposure to more commoditized hardware categories. As recent investments mature, structural reforms continue, and management maintains its disciplined approach to capital allocation, I believe Sony should be capable of generating returns that are more consistently above 10% over the long term. While Sony is unlikely to reach the exceptionally high ROIC levels achieved by asset-light software or consumer brand companies, its combination of valuable intellectual property, technological leadership, and improving capital efficiency should support attractive long-term returns on invested capital.

The next numbers are the book value + dividend. In my old format this was known as the equity growth rate. It was the most important of the four growth rates I used to use in my analyses, which is why I will continue to use it moving forward. As you are used to see the numbers in percentage, I have decided to share both the numbers and the percentage growth year over year. To put it simply, equity is the part of the company that belongs to its shareholders – like the portion of a house you truly own after paying off part of the mortgage. Growing equity over time means the company is becoming more valuable for its owners. So, when we track book value plus dividends, we’re essentially looking at how much value is being built for shareholders year after year. Sony's equity has generally increased over the past decade, although it has experienced declines in fiscal years 2022 and 2026. While these declines may initially appear concerning, they largely reflect accounting effects and capital allocation decisions rather than deterioration in the underlying business. The decline in fiscal year 2022 was primarily driven by changes in the value of financial assets, foreign currency translation adjustments, and other items that flow directly through equity rather than the income statement. Sony generates a significant portion of its revenue and owns substantial assets outside Japan, so movements in exchange rates can have a meaningful impact on reported equity even when the underlying businesses continue to perform well. The decline in fiscal year 2026 was mainly caused by two factors. First, Sony spun-off most of its financial services business into an independent company. Because that business is no longer fully owned by Sony, its assets are no longer included in Sony's balance sheet, which reduced the company's reported equity. Second, Sony continued to return cash to shareholders through share repurchases. Since buybacks reduce the amount of equity on the balance sheet, these factors more than offset the profits Sony generated during the year. Despite these fluctuations, Sony continues to generate solid profits and strong cash flows. Management has consistently reinvested capital into areas with attractive long-term growth prospects, including PlayStation, image sensors, music, and entertainment intellectual property, while also returning excess capital to shareholders when appropriate. As a result, movements in equity should not be viewed in isolation but alongside the company's overall capital allocation strategy. Looking ahead, I expect Sony's equity to continue increasing over the long term, although individual years may still show declines. The company generates healthy earnings and continues to invest in businesses that should support long-term value creation. However, reported equity will likely remain affected by foreign exchange movements, strategic transactions, and shareholder returns such as dividends and share repurchases. These factors can create short-term volatility, but they do not necessarily indicate any deterioration in Sony's competitive position or financial strength.

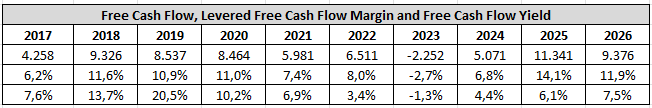
Finally, we will analyze the free cash flow. Free cash flow, in short, refers to the cash that a company generates after covering its operating expenses and capital expenditures. I use levered free cash flow margin because I believe that margins offer a better understanding of the numbers. Free cash flow yield refers to the amount of free cash flow per share that a company is expected to generate in relation to its market value per share. Sony has historically generated strong free cash flow despite operating in several capital-intensive industries. This is largely due to the company's diversified business model, which combines businesses that generate highly recurring cash flows with businesses that require larger investments. PlayStation benefits from digital game sales, subscriptions, and online services, while the Music segment generates recurring royalties from streaming and music publishing. These businesses require relatively modest ongoing investment compared to the cash they generate. Together with profitable operations in image sensors, they provide Sony with a solid foundation for cash generation. Another reason Sony generates strong free cash flow is its disciplined capital allocation. Management carefully evaluates investment opportunities and prioritizes projects that strengthen Sony's competitive advantages in areas such as gaming, entertainment, and image sensors. Although these investments can be substantial, they are typically focused on businesses where Sony holds leading market positions and expects attractive long-term returns. The negative free cash flow in fiscal year 2023 was primarily the result of unusually high investments rather than weaker underlying operations. During the year, Sony invested heavily in expanding production capacity for its image sensor business while also spending more on other long-term growth initiatives. At the same time, more cash was tied up in inventory and other day-to-day business activities, leaving less cash available. As a result, Sony temporarily spent more cash than it generated from its operations. Free cash flow recovered strongly in fiscal years 2024 and 2025 as these temporary pressures eased and the underlying business continued to perform well. Fiscal year 2026 saw free cash flow decline compared to the record level achieved in the previous year. However, this was largely a normalization rather than a deterioration in the business. Sony continued investing in strategic growth areas while generating strong operating cash flow, and free cash flow remained well above the levels seen through most of the past decade. Looking ahead, I expect Sony to remain a strong generator of free cash flow. The company continues to increase the share of earnings coming from higher-margin and more recurring businesses such as PlayStation Network, digital game sales, music streaming, music publishing, and entertainment intellectual property. At the same time, management has become increasingly focused on capital efficiency and carefully reviews investment spending to ensure it supports long-term shareholder value. Free cash flow will likely fluctuate from year to year because Sony continues to invest in areas such as image sensors, content creation, and technology. However, the company's diversified portfolio of businesses, recurring revenue streams, and disciplined capital allocation should support healthy cash generation over the long term. Sony primarily uses its free cash flow in two ways. First, it reinvests in the business through investments in image sensor production capacity, gaming, entertainment content, technology, and strategic acquisitions that strengthen its competitive position. Second, Sony returns capital to shareholders through a steadily growing dividend and share repurchases. Management has identified shareholder returns as one of its key priorities and recently increased both the pace of dividend growth and the size of its share buyback program. At the same time, Sony maintains the financial flexibility to continue investing in long-term growth opportunities while rewarding shareholders, which I believe reflects a disciplined and balanced approach to capital allocation. The free cash flow yield suggests that Sony is trading at an attractive valuation. However, we will revisit valuation later in the analysis.
Debt
Another important area to investigate is debt, and we want to see whether a business has a reasonable level of debt that could be paid off within three years. To assess this, we divide total long-term debt by earnings. When applying this measure to Sony, the result shows that it would take approximately 0,8 years of earnings to pay off its long-term debt. This is well below the three-year threshold, which means that debt is not a concern when investing in Sony. In fact, Sony has maintained a debt level below this threshold for more than a decade, despite making significant investments and acquisitions during that time. Combined with the company's strong cash generation, this gives Sony considerable financial flexibility to continue investing in future growth while also returning capital to shareholders.
Unlock Exclusive Seeking Alpha Discounts – Level Up Your Investing With Zero Risk
If you’ve been thinking about improving your investing process, this is the easiest way to start. These offers are only available through my links, and the Premium plan even comes with a 100% risk-free 7-day trial. Try everything for a week, and if it’s not for you, just cancel. You lose nothing.
1) Seeking Alpha Premium — Try It Free for 7 Days
Access the tools I personally use every day:
• Earnings transcripts
• Stock screeners
• Deep-dive analysis
• Portfolio tracking
• Market news with context that actually matters
Special Price: $269/year (normally $299) + 7-day free trial (for new users only)
Try Premium Free for 7 Days → HERE
(Explore everything — cancel anytime during the trial and pay $0.)
2) Alpha Picks — Proven Stock Ideas
This stock-picking service has delivered +287% returns vs. the S&P 500’s +77% (July 2022–Nov 2025).Great for investors who want curated, long-term picks backed by data.
Special Price: $449/year (normally $499)
Get Alpha Picks → HERE
(Although Alpha Picks doesn’t offer a free trial, its historical outperformance means the subscription can often pay for itself quickly if results persist. For many investors, the potential return far outweighs the upfront cost).
3) Premium + Alpha Picks Bundle — Best Value
Get both services together and save $159.Perfect if you want both broad tools and high-conviction stock ideas.
Special Price: $639/year (normally $798)
Get the Bundle → HERE
(This bundle doesn’t include a free trial, but it gives you both services at a $159 discount. You get Premium’s in-depth research plus Alpha Picks’ high-performing recommendations, making it the most comprehensive option for serious investors.)
Risks
Competition is a risk for Sony because the company operates in several highly competitive industries where success depends on continuously attracting consumers, creators, and business partners. Although Sony holds leading positions in gaming, music, image sensors, and entertainment, each of these markets evolves rapidly. Competitors are constantly investing in new technologies, content, and platforms, making it essential for Sony to continue innovating in order to maintain its competitive position. Gaming represents one of Sony's most important competitive battlegrounds. PlayStation competes primarily with Microsoft's Xbox and Nintendo's gaming platforms, but competition increasingly extends beyond console sales. Today, success depends on building attractive digital ecosystems that keep players engaged through exclusive games, online services, subscriptions, and social features. Competitors continue investing heavily in game development studios and content libraries to strengthen their own platforms. If Sony is unable to develop compelling exclusive games, maintain strong relationships with third-party developers, or continue expanding PlayStation Network and PlayStation Plus, it could lose users, reducing both software sales and the high-margin recurring revenue generated through its digital ecosystem. Sony also faces intense competition in film, television, and anime. Sony Pictures competes with major Hollywood studios as well as global streaming companies such as Netflix, Disney, and Amazon, all of which are investing billions of dollars each year in original content. Competition extends beyond attracting viewers. Studios must also compete for talented actors, directors, producers, writers, and valuable intellectual property. As more companies produce their own content, securing attractive distribution opportunities has become increasingly difficult. If Sony is unable to consistently create successful films, television series, and anime, profitability within these businesses could become more volatile. The music industry is similarly competitive. Sony Music competes primarily with Universal Music Group and Warner Music Group to attract and retain successful artists and songwriters. At the same time, music consumption is increasingly controlled by streaming platforms such as Spotify, Apple Music, and YouTube. While streaming has created recurring revenue opportunities, it also means that record labels must continually invest in discovering new artists, developing existing talent, and expanding their music catalogs. Since consumer tastes constantly evolve, there is no guarantee that investments in new artists or music rights will generate attractive returns. Competition is also significant in Sony's technology businesses. In consumer electronics, the company competes with global manufacturers such as Samsung, Apple, Canon, Xiaomi, and many others. Consumer preferences evolve quickly, product life cycles are relatively short, and pricing pressure remains intense. Sony therefore needs to continually develop products that offer meaningful improvements in image quality, sound quality, design, and user experience while keeping costs under control. Even Sony's leadership in image sensors is not guaranteed. The company has built its position through decades of technological innovation and significant investments in research, development, and manufacturing capacity. However, competitors continue investing aggressively to narrow the technology gap. If rival companies develop comparable image sensor technology or if Sony fails to anticipate changing customer requirements in areas such as smartphones, automotive systems, and industrial applications, the company could lose market share or face increased pricing pressure.
Macroeconomic conditions and geopolitical developments are a risk for Sony because the company operates globally and sells many products and services that consumers can postpone purchasing during periods of economic uncertainty. Sony generates revenue across gaming, consumer electronics, music, films, image sensors, and other businesses, with significant exposure to North America, Europe, Japan, and Asia. While this geographic diversification reduces dependence on any single market, it also means that economic weakness in one or more major regions can weigh on the company's overall performance. Many of Sony's products are discretionary purchases rather than everyday necessities. During periods of high inflation, rising interest rates, or economic recession, consumers often reduce spending on products such as PlayStation consoles, televisions, cameras, headphones, and smartphones. They may also delay purchases of games or spend less on entertainment. Businesses can likewise reduce investments in professional imaging equipment and other technology products. Lower demand across several of Sony's business segments could lead to slower revenue growth and weaker profitability. Macroeconomic conditions can also affect Sony's entertainment businesses. Although music streaming and gaming subscriptions tend to be relatively resilient, spending on movie tickets, digital entertainment, and physical media may weaken during periods of lower consumer confidence. In addition, companies often reduce advertising budgets during economic downturns, which can affect parts of Sony's media businesses that generate advertising revenue. Geopolitical developments present another important risk. Sony designs, manufactures, and sells products around the world, relying on a global supply chain that spans many countries. Components are sourced from numerous suppliers, while many products are manufactured or assembled in Asia before being shipped to customers worldwide. Armed conflicts, trade disputes, tariffs, sanctions, or deteriorating political relationships between major economies can disrupt these supply chains, increase transportation costs, or make it more expensive to manufacture and distribute products. They can also delay deliveries and reduce Sony's ability to respond quickly to changes in customer demand. Trade policies represent another source of uncertainty. Changes in tariffs or import restrictions can increase Sony's costs or reduce demand in important markets. Because geopolitical conditions can change rapidly, management has emphasized the importance of remaining flexible and adapting quickly rather than relying on a single long-term assumption. While Sony continuously monitors geopolitical developments and adjusts its operations where necessary, sudden policy changes remain difficult to predict. Sony is also exposed to fluctuations in exchange rates because it generates a large share of its revenue outside Japan while reporting its financial results in Japanese yen. Movements in currencies can affect both reported revenue and earnings even when the underlying businesses perform well. Although these fluctuations do not necessarily change the long-term value of the business, they can create meaningful volatility in Sony's reported financial results from year to year.
Supply chain and component availability are a risk for Sony because the company depends on a complex global network of suppliers to manufacture and deliver many of its products. PlayStation consoles, cameras, televisions, smartphones, and image sensors all require thousands of individual components sourced from third-party suppliers around the world. If key components become unavailable, significantly more expensive, or delayed, Sony may struggle to meet customer demand, increase production, or maintain profitability. One of the most important challenges today is the sharp increase in memory prices. The rapid expansion of artificial intelligence infrastructure has significantly increased demand for memory chips, creating supply shortages across industries including gaming, smartphones, laptops, and other electronics. Management has highlighted this as one of the biggest near-term challenges because higher memory prices directly increase the cost of manufacturing products such as PlayStation consoles. Sony has managed to secure sufficient memory supplies for the current fiscal year and has negotiated pricing with suppliers, limiting the immediate impact. However, management also expects memory prices to remain elevated due to continued supply shortages, which could put pressure on margins if costs remain high for an extended period. Sony also depends on suppliers for many highly specialized components that are produced by only a limited number of companies. Some of these parts require advanced manufacturing capabilities or have limited production capacity, making them difficult to replace. If one of these suppliers experiences production problems or cannot deliver enough components, Sony may struggle to manufacture sufficient quantities of its products. This could delay product launches, reduce sales, or force Sony to redesign products using alternative components. Another challenge is accurately predicting customer demand. Sony must order many components months before products reach consumers. If demand turns out to be stronger than expected, the company may not have enough components to produce sufficient quantities, resulting in missed sales opportunities. On the other hand, if demand is weaker than expected, Sony may be left with excess inventory that eventually needs to be sold at discounted prices or written down, reducing profitability. While Sony works closely with suppliers, secures long-term supply agreements where possible, and continuously adjusts its procurement and production plans, it cannot eliminate these risks entirely. As its products become increasingly advanced and rely on more specialized components, ensuring reliable access to those components will remain essential. Prolonged component shortages, persistently high memory prices, rising input costs, or inaccurate demand forecasts could reduce Sony's sales, pressure margins, and make it more difficult for the company to meet customer demand.
Reasons to invest
Gaming is a reason to invest in Sony because it has become one of the company's largest and most profitable businesses while still offering significant long-term growth opportunities. At the center of this business is the PlayStation ecosystem, which combines hardware, digital software, online services, subscriptions, and first-party game development into a highly integrated platform. Rather than simply selling consoles every several years, Sony has built a recurring revenue business that continues generating cash throughout the life of each console generation. PlayStation continues to expand its global user base. By the end of fiscal year 2026, cumulative PlayStation 5 sales had exceeded 93 million units, while the PlayStation platform reached approximately 125 million monthly active users. Importantly, Sony is not only benefiting from new PlayStation 5 users but also from millions of players who remain active on earlier generations of PlayStation hardware. This large installed base creates a growing audience that can be monetized through game sales, downloadable content, subscriptions, and digital services. One of the most attractive aspects of Sony's gaming business is the increasing share of recurring revenue. Through PlayStation Plus, PlayStation Store, downloadable content, and in-game purchases, Sony earns revenue long after a console has been sold. Digital game sales also tend to be more profitable than physical copies because they eliminate manufacturing, packaging, and retail distribution costs. As more players purchase games digitally and subscribe to PlayStation Plus, a larger portion of Sony's gaming revenue becomes recurring and less dependent on the timing of new console launches. Sony also owns one of the strongest collections of gaming intellectual property in the industry. Franchises such as God of War, Horizon, Gran Turismo, The Last of Us, Ghost of Tsushima, Marvel's Spider-Man, and Wolverine help differentiate PlayStation from competing platforms while generating revenue across multiple console generations. These franchises can also be extended into television series, films, merchandise, and other entertainment formats, allowing Sony to monetize successful intellectual property across several business segments. Upcoming releases such as Marvel's Wolverine and future titles from PlayStation Studios provide additional opportunities to attract players and strengthen engagement across the platform. Another reason for optimism is the continued expansion of the global gaming market. As internet access improves and incomes rise in emerging markets, millions of new consumers are gaining access to video games. Sony believes this creates a long runway for industry growth, particularly as gaming becomes an increasingly mainstream form of entertainment across all age groups and regions. Artificial intelligence could become another important growth driver. Management believes AI will significantly reduce the time and cost required to develop games, allowing studios to create more ambitious experiences while lowering barriers for new developers to enter the industry. A larger number of games and more diverse content should make gaming even more attractive to consumers and expand the overall market. As one of the world's largest gaming platforms, Sony is well positioned to benefit from this trend. More games increase the value of the PlayStation ecosystem, attracting more players and creating additional opportunities to generate revenue through digital game sales, subscriptions, and network services. Perhaps the biggest advantage of Sony's gaming business is that it has evolved beyond a traditional console manufacturer into a digital entertainment platform. As the installed base grows, each additional user increases the potential value of the ecosystem through higher digital sales, subscription revenue, and network effects.
Music is a reason to invest in Sony because it has built one of the world's largest and most valuable music businesses, generating highly recurring revenue from both recorded music and music publishing. Unlike many entertainment businesses that rely on continually creating new hit products, successful songs can generate cash flows for decades through streaming, radio, television, films, commercials, video games, and live performances. This gives Sony a stable and growing source of earnings that complements its more cyclical businesses. Sony operates two highly attractive music businesses. Sony Music Entertainment owns the rights to recorded music from many of the world's most successful artists, while Sony Music Publishing owns or administers the rights to the underlying musical compositions. Together, these businesses generate royalties whenever songs are streamed, broadcast, performed live, or licensed for use in films, television programs, advertisements, and video games. Because the same song can be monetized repeatedly across multiple platforms and countries, music generates recurring revenue with relatively limited ongoing investment. Sony's catalog includes some of the most iconic artists in music history. Through Sony Music Entertainment and Sony Music Publishing, the company owns or administers music from artists such as Michael Jackson, Bob Dylan, Bruce Springsteen, Beyoncé, Adele, Harry Styles, Celine Dion, Billy Joel, Whitney Houston, AC/DC, Pink Floyd, Queen, and many others. In recent years, Sony has continued strengthening its catalog through major acquisitions, including the music catalogs of Pink Floyd and Queen. These evergreen catalogs continue generating royalties decades after the music was originally released and often become more valuable as streaming platforms expand globally. Streaming remains one of the biggest long-term growth drivers for Sony's music business. Every year, more consumers around the world subscribe to music streaming services such as Spotify, Apple Music, Amazon Music, and YouTube Music. As streaming penetration continues to increase, Sony benefits whenever listeners play songs from its extensive catalog. Management expects the global music market to continue growing at a mid- to high-single-digit rate over the long term and intends to continue investing in high-quality music catalogs to support stable earnings growth. Another attractive characteristic of Sony's music business is its resilience. While new hit songs remain important, a large share of revenue comes from established catalogs that continue attracting listeners year after year. Popular songs are often rediscovered by new generations through films, television series, social media, and streaming playlists. For example, management expects the Michael Jackson biopic to increase global streaming of Michael Jackson's music, demonstrating how successful entertainment releases can create renewed interest in existing catalogs and generate additional royalty income. Sony also benefits from strong relationships with artists, songwriters, producers, and digital streaming platforms. Through labels such as Columbia Records, RCA Records, Epic Records, and independent artist platforms including The Orchard and AWAL, Sony supports artists throughout their careers while expanding its reach across both major and independent music. This broad ecosystem allows Sony to discover new talent while continuing to monetize one of the industry's deepest music catalogs. Sony continues to invest aggressively in expanding its music business. In addition to acquiring valuable music rights, the company recently partnered with GIC, Singapore's sovereign wealth fund, to accelerate future investments in music intellectual property. Management believes that owning high-quality music catalogs will remain an attractive long-term investment because these assets generate recurring cash flows, benefit from the continued growth of streaming, and can be monetized across an expanding range of digital platforms.
Imaging & Sensing Solutions is a reason to invest in Sony because it combines technological leadership, high barriers to entry, and several long-term growth opportunities. Sony is the global leader in CMOS image sensors, supplying many of the world's leading smartphone manufacturers and holding a dominant position in the premium market. While image sensors are already an important contributor to Sony's earnings, management believes the business still has significant growth potential as demand expands beyond smartphones into areas such as automotive systems, industrial automation, robotics, and artificial intelligence. The foundation of Sony's leadership is its ability to continuously develop more advanced image sensors. Modern image sensors do far more than simply capture photographs. They determine how well a smartphone performs in low light, how accurately a car detects pedestrians, and how effectively industrial robots and security systems interpret their surroundings. Sony has spent decades refining every aspect of image sensor technology, from pixel design and manufacturing processes to stacking technologies and packaging. Management believes this combination of expertise is extremely difficult for competitors to replicate because it requires excellence across research, development, manufacturing, and production rather than in just one area. Although smartphones remain the largest market for Sony's image sensors, the business continues to benefit from structural trends even as global smartphone unit sales have matured. Consumers increasingly expect better cameras, encouraging smartphone manufacturers to use larger and more advanced sensors that deliver higher image quality, better low-light performance, improved dynamic range, and lower power consumption. These premium sensors command higher prices and contribute to stronger profitability for Sony. Beyond smartphones, Sony sees attractive opportunities in several emerging markets. Automotive image sensors are expected to become increasingly important as vehicles adopt more advanced driver assistance systems and gradually move toward higher levels of autonomous driving. Modern vehicles require multiple cameras to monitor the road, detect pedestrians, recognize traffic signs, and support parking and safety systems. At the same time, demand for image sensors is growing in industrial automation, robotics, factory equipment, medical technology, and security systems. As artificial intelligence becomes more widespread, cameras are increasingly becoming the "eyes" of intelligent machines, creating additional long-term demand for high-performance image sensors. Management also believes artificial intelligence will become an important growth driver for the business. While AI receives much of the attention through software, intelligent systems first need high-quality visual information to understand the physical world. Sony's image sensors provide that information by capturing images that AI systems can analyze and interpret. As robotics, autonomous machines, and other forms of physical AI become more common, management expects image sensors to play an increasingly important role, creating new opportunities beyond the traditional smartphone market. An important recent development is Sony's strategic partnership with TSMC to develop and manufacture next-generation image sensors. Historically, Sony has carried much of the cost of expanding manufacturing capacity itself. Through the partnership, Sony intends to combine its expertise in image sensor design with TSMC's world-leading semiconductor manufacturing capabilities. Management expects this collaboration to improve technological competitiveness while reducing the amount of capital required to expand production. This supports Sony's broader strategy of making the business less capital intensive, improving profitability, and increasing financial flexibility without sacrificing its technology leadership.
Support the Blog
I want to keep the blog free and accessible for everyone. If you enjoy the content and would like to support it, you can buy me a cup of coffee through PayPal. Every little bit helps and is truly appreciated!

Valuation
Now it is time to calculate the share price. I perform three different calculations that I learned at a Phil Town seminar. If you want to make the calculations yourself for this or other stocks, you can do so through the tools page on my website, where you have access to all three calculators for free.
The first is called the Margin of Safety price, which is calculated based on earnings per share (EPS), estimated future EPS growth, and estimated future price-to-earnings ratio (P/E). The minimum acceptable rate of return is 15%. I chose to use an EPS of 1,08, which is from the fiscal year 2026. I have selected a projected future EPS growth rate of 8%. Finbox expects EPS to grow by 7,5% in the next five years. Additionally, I have selected a projected future P/E ratio of 16, which is double the growth rate. This decision is based on Sony's historically higher price-to-earnings (P/E) ratio. Finally, our minimum acceptable rate of return has already been established at 15%. After performing the calculations, we determined the sticker price (also known as fair value or intrinsic value) to be $9,22. We want to have a margin of safety of 50%, so we will divide it by 2. This means that we want to buy Monster at a price of $4,61 (or lower, obviously) if we use the Margin of Safety price.
The second calculation is known as the Ten Cap price. The rate of return that a company owner (or stockholder) receives on the purchase price of the company essentially represents its return on investment. The minimum annual return should be at least 10%, which I calculate as follows: The operating cash flow last year was 12.259, and capital expenditures were 2.884 I attempted to analyze their annual report to calculate the percentage of capital expenditures allocated to maintenance. I couldn't find it, but as a rule of thumb, you can expect that 70% of the capital expenditures will be allocated to maintenance purposes. This means that we will use 2.019 in our calculations. The tax provision was 2.313. We have 5.907 outstanding shares. Hence, the calculation will be as follows: (12.259 – 2.019 + 2.313) / 5.907 x 10 = $21.25 in Ten Cap price.
The final calculation is referred to as the Payback Time price. It is a calculation based on the free cash flow per share. With Sony's free cash flow per share at $1,59 and a growth rate of 8%, if you want to recoup your investment in 8 years, the Payback Time price is $18,27.
Conclusion
I believe that Sony is an intriguing company with a great management team. The company has built its moat through its valuable intellectual property, platform ecosystems, technological leadership, production and distribution scale, strong relationships with creators and business customers, and its ability to leverage these advantages across multiple forms of entertainment. Sony's ROIC has historically been solid rather than exceptional, reflecting its diversified and relatively capital intensive business model. With recent investments beginning to mature and management placing greater emphasis on capital efficiency, I believe Sony has the potential to generate returns that are more consistently above 10% over the long term. Sony has consistently generated strong free cash flow, supported by its growing mix of recurring revenue businesses and disciplined capital allocation. While cash generation may fluctuate due to investments in future growth, I believe Sony is well positioned to remain a strong free cash flow generator over the long term. Competition is a risk because Sony competes against some of the world's largest technology and entertainment companies across gaming, music, film, and consumer electronics. Stronger products, content, or ecosystems from competitors could reduce market share and put pressure on both revenue and margins. Macroeconomic conditions and geopolitical developments are also a risk because Sony generates revenue across many regions and industries that are sensitive to consumer spending and global trade. Economic slowdowns, geopolitical tensions, or currency fluctuations could reduce demand, increase costs, and weigh on the company's financial performance. Supply chain and component availability are another risk because Sony depends on a global network of suppliers for many critical components used in its products. Component shortages, persistently high memory prices, or delays in securing key parts could increase costs, reduce production, and make it more difficult for Sony to meet customer demand. Gaming is one of Sony's strongest growth drivers because the company has built a highly profitable ecosystem that generates recurring revenue through digital game sales, subscriptions, and online services. As the PlayStation user base continues to expand and engagement increases, I believe the gaming business is well positioned to deliver long term growth and cash generation. Music is another reason to invest because Sony owns one of the world's most valuable music catalogs, generating highly recurring royalty income from streaming, licensing, and publishing. As global music streaming continues to grow and the company expands its catalog through acquisitions, I believe the Music segment is well positioned to deliver stable long term earnings growth. Imaging & Sensing Solutions is also a reason to invest because Sony is the global leader in image sensors, benefiting from high barriers to entry, technological leadership, and growing demand across smartphones, automotive, robotics, and artificial intelligence. As these markets expand and the partnership with TSMC improves capital efficiency, I believe this business is well positioned to deliver attractive long term growth. Overall, I believe there are many things to like about Sony, and while the shares may not appreciate rapidly, I believe they could be a good addition to a well diversified portfolio if they can be purchased below the Ten Cap price of $21.
Follow my investment journey
I hope you enjoyed this analysis. I regularly publish in depth company analyses on InvestSeekers and share updates on the companies I follow.
If you would like to see what I currently invest in, I publicly share my portfolio and any changes I make over time. You can also learn how to follow or copy my portfolio through the investment platform I use.
Stay updated
If you enjoy my company analyses, you can sign up for my free newsletter to receive my latest analyses, investment ideas, and other updates directly in your inbox. Subscribers may also receive selected content before it is published publicly on InvestSeekers. Simply scroll to the bottom of this page and sign up.
Watch on YouTube
If you prefer a faster and more visual way to understand a company, I also publish videos on YouTube covering Nordic companies that receive relatively little coverage in English. Each video provides an understandable overview of the business, financials, risks, reasons to invest, and valuation.
Follow me on X
I also share more frequent investment updates on X, including company news, new analyses, and changes I make to my portfolio.
A cause I support
If you found my analysis valuable and would like to support a good cause, I encourage you to consider making a small donation to ADEPAC. It is a charity I know firsthand, and I have seen the valuable work they do despite having very limited resources.
Even a small donation can make a difference.

Comments