Norwegian Air Shuttle: The Nordic Low Cost Airline
Norwegian Air Shuttle is one of the leading airline groups in the Nordics, connecting millions of passengers across an extensive network of Nordic and European destinations. Through Norwegian and Widerøe, the group combines low cost air travel with a strong regional network, while its modernizing fleet, growing loyalty ecosystem, and focus on operational efficiency support its competitive position. With disciplined capacity growth, increasing fleet ownership, and an expansion into packaged holidays through the planned acquisition of Nordic Leisure Travel Group, Norwegian aims to become a broader Nordic travel company while maintaining its focus on profitability. The question remains: Does this Nordic travel company deserve a spot in your portfolio?
This is not financial advice. I am not a financial advisor, and I publish these analyses to document my own research and share my thoughts with readers and followers. If you are considering investing in any of the companies or ideas discussed, you should always do your own research and, if necessary, consult a qualified financial professional. All investing involves risk, and you may lose some or all of the money you invest.
For full disclosure, I do not own shares in Norwegian Air Shuttle at the time of writing this analysis. I publicly share my investment portfolio, including all of my current holdings and changes I make over time. If you are interested in seeing what I currently invest in and learning how you can follow or copy my portfolio, you can read more here.
The Business
Norwegian Air Shuttle was founded in 1993 and has developed into one of the leading airline groups in the Nordic region. Following a major restructuring in 2021, the company moved away from its previous strategy of aggressive international expansion and long-haul flying and refocused the business around its strongest markets in the Nordics. Today, the Norwegian Group consists primarily of two airlines, Norwegian Air Shuttle and Widerøe, which Norwegian acquired in 2024. Together, they provide a broad network of domestic, regional, and international flights across Norway, Sweden, Denmark, and Finland, as well as connections from the Nordics to major leisure and city destinations throughout Europe and nearby countries. The group carried approximately 27,3 million passengers in 2025, of which around 23 million traveled with Norwegian and 4,1 million with Widerøe. Norwegian Air Shuttle primarily operates a low-cost, short-haul point-to-point model. Rather than attempting to compete across the entire European aviation market, the company concentrates its capacity on routes where it has historically generated attractive economics and where passenger volumes are sufficiently large to support frequent service. Its network consists of close to 350 routes, giving Norwegian one of the broadest networks connecting the Nordic countries with European destinations. Norwegian is the largest airline group by capacity in Norway and the second largest in Denmark, Sweden, and Finland, giving the company significant scale across each of its core markets. Norwegian serves both leisure and business passengers, although leisure travel remains particularly important. The company connects Nordic cities with popular European destinations while also operating domestic and intra-Nordic routes. This combination allows Norwegian to serve customers traveling for holidays, visiting friends and relatives, and increasingly for business purposes. A central part of Norwegian's business model is maintaining a relatively simple and efficient cost structure. The airline operates a single-family fleet consisting of Boeing 737-800 and Boeing 737 MAX 8 aircraft, with 95 aircraft in the Norwegian fleet at the end of 2025. Using closely related aircraft reduces operational complexity because pilots, maintenance operations, spare parts, training, and scheduling can be standardized across much of the fleet. Norwegian also concentrates aircraft and crew at strategically located bases across the Nordics and selected European markets, helping improve aircraft and labor utilization. These efficiencies allow Norwegian to maintain a lower cost base than many traditional network airlines while offering a broader customer proposition than many ultra-low-cost carriers. Widerøe adds a different but highly complementary business to the group. Widerøe is Norway's oldest airline and the largest regional airline in Scandinavia, operating more than 50 destinations and close to 120.000 flights during 2025. Its network is particularly important in regional Norway, where geography, long distances, mountains, fjords, and relatively limited alternative transportation make aviation an essential part of the country's transportation infrastructure. Widerøe operates both commercially viable routes and public service obligation routes supported through government contracts, particularly between smaller communities and regional centers. Its fleet of 51 aircraft at the end of 2025 consisted primarily of De Havilland Dash 8 aircraft capable of operating from Norway's network of small short-runway airports, supplemented by three Embraer E190-E2 jets. Widerøe also operates Widerøe Ground Handling, which provides ground services at 41 Norwegian airports for Widerøe, Norwegian, and external airlines. The acquisition creates a complementary network structure. Widerøe can transport passengers from smaller Norwegian communities into larger airports such as Oslo, Bergen, Bodø, and Tromsø, while Norwegian can carry those passengers onward to destinations elsewhere in the Nordics and Europe. Norwegian's new distribution platform strengthens this relationship by allowing customers to book itineraries combining Norwegian and Widerøe flights through Norwegian's website. Over time, deeper integration of booking, loyalty, and network planning should make the two airlines increasingly valuable to one another while preserving their separate operating models. Widerøe also improves the seasonality of the overall group. Norwegian's leisure-focused business generates substantially stronger demand during the European summer travel season, whereas Widerøe's regional operations and public service routes have a more stable demand profile throughout the year. Combining the two therefore creates a somewhat more balanced business than Norwegian Air Shuttle would have on its own. The group also benefits from increased scale in areas that do not need to remain separate. Norwegian has identified opportunities to share facilities, organizational functions, procurement, technology, and other support activities. A larger combined group has greater purchasing power when negotiating with airports, suppliers, technology providers, and other vendors, creating opportunities to lower unit costs while maintaining Norwegian and Widerøe as distinct airlines. Another important part of the customer proposition is Norwegian Reward, the group's loyalty program, which has more than four million members across the Nordics. Norwegian has expanded the program through initiatives such as Spenn, a digital loyalty currency developed together with Strawberry and Reitan. The broader ecosystem allows customers to earn and use rewards across travel and other everyday spending categories, strengthening the relationship between Norwegian and its customers. Combined with a broad route network, competitive fares, and strong operational performance, the loyalty program supports Norwegian's ambition to become the preferred airline for Nordic travelers. Norwegian's competitive moat is primarily built on its Nordic network, scale, cost position, brand and loyalty ecosystem, and the complementary regional infrastructure provided by Widerøe. It is important to recognize that airlines generally do not possess the same degree of pricing power or structural protection as companies in industries with high switching costs or proprietary products. Customers can compare airline prices easily, and price remains an important factor when choosing flights. Norwegian's moat should therefore be viewed primarily as a relative competitive advantage within its core Nordic markets rather than an exceptionally strong global moat. The company's most important advantage is the scale and density of its Nordic network. Norwegian has spent more than two decades developing routes, airport relationships, operational bases, brand awareness, and customer relationships throughout the region. It is the largest airline group by capacity in Norway and among the two largest in each of Denmark, Sweden, and Finland. This scale allows Norwegian to offer a large number of direct routes between Nordic cities and popular European destinations. Network breadth matters because passengers generally prefer direct flights over connecting itineraries when comparable alternatives are available. The more destinations and frequencies Norwegian can offer from its Nordic bases, the more useful the network becomes to customers. Scale also improves the economics of the business. A larger airline can spread technology, administration, marketing, procurement, maintenance capabilities, and other fixed costs across more passengers and flights. It can also negotiate from a stronger position with airports and suppliers. This creates a reinforcing relationship between scale and cost competitiveness: a large network attracts passengers, passenger volumes support more routes and frequencies, and greater scale helps lower costs and makes the network more difficult for smaller competitors to replicate economically. A new entrant could theoretically launch individual routes against Norwegian, but replicating Norwegian's entire Nordic network would require substantial aircraft capacity, airport slots, crews, capital, marketing expenditures, and time without any guarantee that sufficient passenger volumes could be captured from established operators. Widerøe strengthens this network advantage considerably. Its regional network reaches many smaller Norwegian airports that Norwegian's Boeing 737 fleet cannot efficiently serve, including airports with short runways requiring specialized aircraft and operational capabilities. Widerøe therefore provides access to parts of the Norwegian aviation market that are difficult for conventional low-cost airlines to address. Some routes are also operated under public service obligation contracts, creating a more stable component within the group's network. Combining Widerøe's regional reach with Norwegian's domestic and European network creates a hub-and-feed effect even though Norwegian remains primarily a point-to-point airline. A passenger originating in a smaller Norwegian community can travel with Widerøe to a larger airport and continue with Norwegian to another Nordic or European destination. The introduction of interlining through Norwegian's new distribution platform makes this increasingly seamless. As the integration develops, the combined network should become more valuable because Norwegian gives Widerøe passengers access to a much larger European network while Widerøe provides Norwegian with passenger flows from regional Norway that competitors without a comparable feeder network cannot replicate as easily. Norwegian's low-cost operating structure represents another important competitive advantage. Its simplified Boeing 737 fleet reduces complexity across training, maintenance, scheduling, and operations, while a concentrated Nordic network allows the company to utilize aircraft and crews efficiently. This positions Norwegian between two groups of competitors. Against traditional network carriers, Norwegian can compete with a structurally lower cost base and therefore offer attractive fares. Against ultra-low-cost carriers, Norwegian can compete with a stronger local brand, a broader Nordic network, greater frequencies on important routes, and a customer proposition designed specifically around Nordic travelers. This positioning is important because competing solely on price in aviation is difficult to sustain. Norwegian instead aims to combine low costs with sufficient product quality, network breadth, operational reliability, and customer service to give passengers reasons to choose the airline beyond simply purchasing the cheapest available ticket. Brand strength reinforces this advantage. Norwegian has operated in the Nordic market for more than two decades and has become one of the region's most recognizable airline brands. This familiarity matters in an industry where reliability and trust influence purchasing decisions, particularly when price differences between competing flights are relatively small. The company's operational performance supports the brand proposition, with Cirium ranking Norwegian among Europe's ten most punctual airlines in 2025. Norwegian Reward adds another layer of customer retention. With more than four million members in the Nordics, the program gives Norwegian a large direct relationship with frequent travelers and provides customer data that can be used to improve marketing, personalization, and ancillary revenue opportunities. The introduction of Spenn and deeper cooperation with partners such as Strawberry and Reitan expands the usefulness of the loyalty ecosystem beyond flights. As customers accumulate rewards that can be earned and spent across multiple businesses, there is a greater incentive to remain within the ecosystem, modestly increasing switching costs in an industry where customer switching costs are otherwise very low. The acquisition of Widerøe also creates cost advantages that should become more meaningful as integration progresses. Although the two airlines maintain separate operating organizations and distinct fleets suited to their respective networks, the larger group can consolidate selected functions, facilities, procurement, technology, and support services. Management has specifically highlighted increased purchasing power toward suppliers as one source of synergies. These benefits should strengthen as contracts are renegotiated and common systems are introduced. Overall, Norwegian's moat does not come from one dominant advantage but from the interaction between several reinforcing strengths. Its large Nordic customer base supports an extensive network, the extensive network makes Norwegian more attractive to customers, higher passenger volumes create scale economies, scale supports a competitive cost base, Widerøe extends the network into regional markets that are difficult for conventional competitors to serve, and Norwegian Reward increases customer engagement across the combined network. None of these advantages makes Norwegian immune to competition, economic cycles, fuel prices, or aggressive capacity additions from rivals, but together they create a stronger competitive position in the Nordic aviation market than Norwegian's low-cost airline label alone might suggest.
Management
Geir Karlsen serves as the CEO of Norwegian Air Shuttle, a role he assumed in June 2021 after previously serving as the company's Chief Financial Officer. Geir Karlsen brings extensive experience in finance, capital allocation, restructuring, and managing companies in capital intensive and cyclical industries. His background has proven particularly relevant at Norwegian, where he played a central role in the financial reconstruction that transformed the company from a highly leveraged airline pursuing aggressive international expansion into a more focused and financially disciplined Nordic airline group. Before becoming CEO, Geir Karlsen joined Norwegian as Chief Financial Officer in April 2018, at a time when the company was already facing significant financial challenges following years of rapid expansion. Geir Karlsen later served as Acting CEO during 2019 following the departure of founder and longtime CEO Bjørn Kjos, before returning his focus to the finance organization when Jacob Schram became CEO. During the COVID 19 pandemic, Norwegian faced an existential crisis as international travel restrictions severely reduced passenger demand while the company was already carrying substantial financial obligations. Geir Karlsen became one of the central figures in Norwegian's financial reconstruction, which ultimately resulted in the company significantly reducing its debt, raising new capital, abandoning its long haul operations, and emerging with a substantially smaller and more focused business. When Norwegian appointed Geir Karlsen as CEO in June 2021, the board specifically highlighted his successful leadership of the company's financial reconstruction as one of the reasons for selecting him. His appointment therefore represented continuity between the financial restructuring and the strategy Norwegian would pursue afterward. Rather than returning to the aggressive growth strategy that had characterized Norwegian before the pandemic, Geir Karlsen has focused the company on disciplined growth, profitability, cost control, and its strongest geographic markets. Before joining Norwegian, Geir Karlsen built much of his career in shipping and offshore industries, giving him considerable experience with businesses characterized by high fixed costs, cyclical demand, significant capital requirements, and volatile market conditions. Geir Karlsen held several senior finance positions at international companies, including serving as Chief Financial Officer of Golden Ocean Group and Songa Offshore. Immediately before joining Norwegian, Geir Karlsen served as Group Chief Financial Officer of London based Navig8 Group, one of the world's largest shipping pool and commercial management companies. His career across shipping, offshore, and aviation has therefore largely been spent in industries where disciplined capital allocation, balance sheet management, asset utilization, and cost control are critical to long term success. Geir Karlsen holds a degree in Business Administration from BI Norwegian Business School. Since becoming CEO, Geir Karlsen has continued the strategic transformation that began during Norwegian's reconstruction. The company has concentrated its operations around short haul travel within the Nordics and between the Nordics and European destinations, while prioritizing routes with proven historical profitability. Norwegian has also maintained a relatively simple fleet structure and emphasized cost efficiency rather than pursuing growth for its own sake. This represents a significant change from Norwegian's strategy before the restructuring, when rapid fleet expansion and long haul growth contributed to increasing financial leverage and complexity. Under Geir Karlsen's leadership, Norwegian has instead sought to build a business capable of generating sustainable profitability throughout the aviation cycle while maintaining the low cost structure that remains central to the company's competitive positioning. One of the most important strategic decisions under Geir Karlsen has been the acquisition of Widerøe, which was completed in 2024. The acquisition strengthened Norwegian's position in the Nordic aviation market by combining Norwegian's extensive domestic, Nordic, and European network with Widerøe's leading regional network in Norway. Rather than fully integrating the two airlines operationally, Norwegian has maintained Widerøe as a separate airline while pursuing synergies in areas where greater scale creates economic benefits. These include procurement, facilities, organizational functions, distribution, and selected support activities. The introduction of Norwegian's new distribution platform has also enabled customers to book combined Norwegian and Widerøe journeys directly through Norwegian's website, strengthening the commercial benefits of owning the two complementary networks. This approach reflects the broader financial discipline that has characterized Geir Karlsen's leadership, with the focus placed on extracting economic benefits from greater scale while preserving the operating characteristics that make Widerøe valuable. The financial development of Norwegian since the reconstruction provides evidence that the more disciplined strategy has produced results. The company has returned to sustainable profitability, strengthened its financial position, and reached a point where it can once again return capital to shareholders. This represents a significant change from the financial distress Norwegian faced only a few years earlier and reflects the greater emphasis on cost control, profitability, and prudent capital management under Geir Karlsen's leadership. Geir Karlsen also has a direct financial interest in the company's long term development. At the end of 2025, Geir Karlsen owned 651.478 Norwegian shares and held approximately 3,8 million options, creating some alignment between management and shareholders. Given his role in Norwegian's financial reconstruction, extensive experience in capital intensive and cyclical industries, and continued emphasis on profitability and financial discipline, Geir Karlsen appears well suited to lead Norwegian through its current phase of development. Perhaps the most important aspect of Geir Karlsen's leadership is the contrast between the Norwegian of today and the company he inherited. Norwegian previously pursued rapid expansion, long haul flying, and significant fleet growth, ultimately creating a financially fragile business. Under Geir Karlsen, the strategy has become considerably more focused, with management prioritizing its strongest Nordic markets, cost efficiency, profitable routes, balance sheet strength, and disciplined capacity growth. The acquisition of Widerøe has added another avenue for growth, but one that strengthens Norwegian's existing Nordic position rather than taking the company into an entirely new market. For shareholders, maintaining this financial and strategic discipline will be particularly important in an airline industry where excessive capacity growth and leverage have historically destroyed significant shareholder value.
The Numbers
The first number we will look into is the return on invested capital, also known as ROIC. We want to see a 10-year history, with all numbers exceeding 10% in each year. Norwegian Air Shuttle clearly does not meet this criterion. ROIC was 3,9% in 2016 before turning negative for several years, reaching as low as minus 21,0% in 2021. However, the development has improved considerably since the company's restructuring, with ROIC recovering from minus 2,4% in 2022 to 8,7% in 2023, 7,1% in 2024, and 11,6% in 2025. This means that Norwegian generated an ROIC above our 10% threshold for the first time in the 10-year period in 2025. The historically weak returns can largely be explained by the nature of the airline industry combined with Norwegian's former strategy. Airlines are inherently capital intensive businesses. They require substantial investments in aircraft and other operating assets, while profitability can be relatively thin and volatile. This makes consistently generating high returns on invested capital more difficult than for asset-light businesses. Norwegian made this challenge considerably worse during the years leading up to the pandemic by pursuing an extremely aggressive growth strategy. The company expanded rapidly across Europe and into long-haul markets, significantly increased its fleet, and took on substantial financial obligations to finance this growth. As a result, Norwegian's invested capital increased much faster than its ability to generate sustainable operating profits. The company was therefore already generating negative ROIC in the years before COVID 19, with ROIC falling from 3.9% in 2016 to minus 3,3% in 2017 and minus 7,1% in 2018. The pandemic then dramatically worsened an already difficult situation. Travel restrictions caused passenger traffic to collapse while Norwegian continued to face substantial fixed costs and financial obligations. This resulted in large operating losses and explains the particularly weak ROIC figures between 2020 and 2022. The company ultimately underwent a major financial restructuring in 2021 that fundamentally changed both its balance sheet and business model. Norwegian abandoned long-haul operations, reduced its fleet and debt burden, raised new capital, and refocused the business on short-haul routes within the Nordics and between the Nordics and Europe. Because of these changes, comparing Norwegian's current ROIC directly with the figures from before the restructuring should be done with some caution. Today's Norwegian is financially and operationally very different from the company that generated the poor returns seen during much of the previous decade. The improvement in ROIC since 2022 is therefore particularly noteworthy. Rather than pursuing growth for its own sake, Norwegian now focuses on routes with proven historical profitability while maintaining a simpler operating model centered on a relatively standardized Boeing 737 fleet. The company has also become much more disciplined around capacity, costs, and capital allocation. At the same time, the recovery in air travel following the pandemic has improved aircraft utilization and profitability, allowing Norwegian to generate considerably more earnings from its capital base. The acquisition of Widerøe in 2024 added additional invested capital and contributed to the decline in ROIC from 8,7% in 2023 to 7,1% in 2024. This is not necessarily a negative development because acquisitions often initially increase the capital base before the full earnings contribution and synergies are realized. Widerøe also gives Norwegian a more diversified and less seasonal earnings profile while strengthening the group's position in the Nordic market. Looking ahead, there are reasons to believe Norwegian could sustain a materially higher ROIC than it generated historically, although expecting ROIC to remain above 10% every year would be optimistic given the economics of the airline industry. Management continues to focus on cost efficiency through Program X, while further synergies between Norwegian and Widerøe are expected to support profitability in 2026 and beyond. Norwegian is also integrating the two networks more closely through its new distribution platform, loyalty initiatives, procurement, and shared functions, which should allow the group to generate more earnings from its existing network and infrastructure. Management expects further benefits from these initiatives in the coming years. There is, however, an important counterweight to this. Norwegian is entering another period of significant fleet investment. Deliveries from its large Boeing 737 MAX 8 order are accelerating, and the company intends to own a larger proportion of its aircraft rather than relying as heavily on leases. Owning aircraft can lower Norwegian's total operating costs and increase financial flexibility, but it also increases the amount of capital employed in the business. ROIC will therefore depend on whether the additional operating profits and cost savings generated by these aircraft exceed the increase in invested capital. Norwegian has also been purchasing aircraft that it previously leased, with management stating that these transactions should reduce overall ownership costs. The airline industry itself also makes Norwegian's future ROIC inherently volatile. Fuel prices, foreign exchange movements, wage inflation, aircraft availability, economic conditions, ticket pricing, and competitors adding capacity can all have a substantial effect on profitability while much of the capital invested in aircraft remains fixed. This can be seen even in 2026, when higher fuel costs and other factors have affected earnings despite continued cost improvements. Therefore, I would not assume that the increase from negative ROIC to 11.6% represents the beginning of a steady upward trend. What is more important is that Norwegian appears to have moved from a business model that structurally struggled to earn adequate returns on its capital toward a much more disciplined model capable of generating attractive returns under normal market conditions. The 11,6% ROIC achieved in 2025 is encouraging evidence of this transformation, but Norwegian will need to demonstrate that it can maintain ROIC around or above 10% across an entire aviation cycle before I would consider high returns on invested capital a structural characteristic of the business.

The following numbers represent the book value + dividend. In my previous format, this was The next numbers are the book value + dividend. In my old format this was known as the equity growth rate. It was the most important of the four growth rates I used to use in my analyses, which is why I will continue to use it moving forward. As you are used to see the numbers in percentage, I have decided to share both the numbers and the percentage growth year over year. To put it simply, equity is the part of the company that belongs to its shareholders – like the portion of a house you truly own after paying off part of the mortgage. Growing equity over time means the company is becoming more valuable for its owners. So, when we track book value plus dividends, we’re essentially looking at how much value is being built for shareholders year after year. Norwegian's equity has historically been highly volatile, which reflects the dramatic changes the company has gone through over the past decade. Equity declined in both 2017 and 2018 as Norwegian's aggressive expansion strategy placed increasing pressure on its finances. During this period, Norwegian was rapidly expanding its fleet and international network, including its long haul operations. The strategy required substantial amounts of capital, while the company's profitability deteriorated. Equity recovered significantly in 2019, but this improvement proved temporary as the pandemic created an unprecedented crisis for the airline industry. Norwegian entered 2020 in an already difficult financial position, and the collapse in air travel caused by COVID 19 resulted in enormous losses. These losses were so large that Norwegian ended the year with negative equity. Put simply, the company had lost so much money that the value belonging to shareholders on the balance sheet had been wiped out. Norwegian was therefore forced to restructure the business and strengthen its finances to survive. The large increase in equity in 2021 needs to be viewed in the context of this restructuring rather than as ordinary growth. Norwegian raised new capital, converted debt into shares, reduced its financial obligations, and significantly reshaped its balance sheet. These measures restored positive equity and gave the company a much healthier financial foundation. Therefore, the increase from negative equity in 2020 to positive equity in 2021 should not be viewed in the same way as equity growth generated through profits. What is more encouraging is what has happened since then. Norwegian's equity has increased every year since 2021, rising from 3.270 in 2021 to 7.668 in 2025. This improvement has increasingly been driven by the underlying business rather than financial restructuring. Air travel recovered following the pandemic, Norwegian returned to profitability, and the company adopted a much more disciplined strategy centered on its core Nordic markets, profitable routes, and cost control. When Norwegian generates profits and keeps some of those profits within the business, it gradually builds equity for shareholders. The acquisition of Widerøe should also support Norwegian's ability to build equity over time if the acquisition performs as expected. Widerøe adds another profitable business and provides Norwegian with a more diversified earnings base, including regional operations that are less seasonal than Norwegian's traditional leisure focused business. The combination also provides opportunities to lower costs through procurement, shared facilities, and other synergies. If these initiatives improve the profitability of the combined group, they should also contribute to equity growth over time. It is worth remembering that Norwegian's equity can fluctuate for reasons other than the underlying profitability of the airline. Management has, for example, explained that changes in the value of its fuel and currency hedges can increase or decrease equity. This happened recently when favorable movements in the company's hedges contributed to an increase in equity. These movements can make equity somewhat volatile from year to year, so I would focus more on the long term direction than on any single year's change. Looking ahead, there are good reasons to believe Norwegian can continue building equity, although investors should not expect the very high percentage growth rates seen immediately following the restructuring to continue. The starting point after the financial crisis was exceptionally low, making subsequent percentage increases particularly large. As Norwegian's equity base becomes larger, maintaining those growth rates naturally becomes more difficult, which can already be seen in the slower growth in 2025. More importantly, Norwegian now has a healthier balance sheet, strong liquidity, and a more disciplined business model than it had before the pandemic. Management has also continued to prioritize maintaining a solid balance sheet, which is particularly important for an airline because demand and profitability can fluctuate significantly from year to year. Future equity growth will also depend on how Norwegian chooses to use the cash it generates. As the company's financial position has improved, Norwegian has reached a point where it can return capital to shareholders rather than retaining everything within the business. This means book value itself may not necessarily increase every year, even if Norwegian continues to perform well. However, because dividends are included in the book value plus dividend measure used here, returning cash through dividends will still be captured when assessing shareholder value creation. Overall, the development since 2021 is encouraging. Norwegian has moved from negative equity and a fight for survival to a position where a profitable business is once again building value for shareholders. The key question going forward is whether Norwegian can continue doing so through an entire airline cycle while maintaining the financial discipline that has characterized the company since its restructuring.

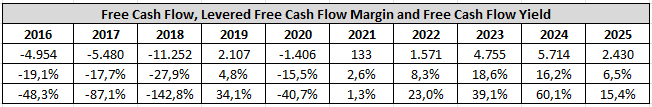
Finally, we will analyze the free cash flow. Free cash flow, in short, refers to the cash that a company generates after covering its operating expenses and capital expenditures. I use levered free cash flow margin because I believe that margins provide a better understanding of the numbers. Free cash flow yield refers to the amount of free cash flow per share that a company is expected to generate in relation to its market value per share. Norwegian's free cash flow has changed significantly over the past decade. The company generated negative free cash flow in 2016, 2017, and 2018 before briefly turning positive in 2019. Free cash flow then became deeply negative again in 2020 before recovering in 2021. Since then, Norwegian has generated positive free cash flow every year, with the free cash flow margin improving significantly in 2023 and 2024 before declining to 6,5% in 2025. The poor free cash flow during the earlier years was closely connected to Norwegian's former growth strategy. The company expanded aggressively, added large numbers of aircraft, and developed a long haul network alongside its European operations. Airlines already require significant amounts of capital, and Norwegian was investing particularly heavily as it tried to grow rapidly. At the same time, profitability was under pressure, meaning that the company was spending substantial amounts of cash without generating enough cash from its operations to compensate. This resulted in negative free cash flow during much of the period before the pandemic. The situation became significantly worse in 2020 when COVID 19 caused air travel to collapse. Norwegian still had substantial costs and financial obligations despite carrying far fewer passengers, resulting in another year of deeply negative free cash flow. The development since 2021 has been much more encouraging. Norwegian emerged from its restructuring as a smaller and more focused airline, abandoning long haul operations and concentrating on short haul routes within the Nordics and between the Nordics and Europe. Rather than pursuing growth for its own sake, Norwegian now focuses more heavily on profitability, cost control, and routes with proven demand. The recovery in passenger traffic following the pandemic has also allowed Norwegian to use its aircraft more efficiently and generate substantially more cash from its operations. As a result, free cash flow has remained positive every year since 2021 and improved considerably as the airline returned to more normal operating conditions. Widerøe has further strengthened the group by adding another profitable airline with a somewhat different demand profile. Widerøe's regional operations are less seasonal than Norwegian's leisure focused network, which should make the group's overall cash generation somewhat more balanced throughout the year. Free cash flow decreased significantly in 2025, falling from 5.714 to 2.430, while the free cash flow margin declined from 16,2% to 6,5%. Importantly, this does not appear to reflect a similar deterioration in the underlying business. One of the main reasons was Norwegian's decision to purchase aircraft that it previously leased. Norwegian entered the year owning only a small number of aircraft but substantially increased the number of aircraft it owned during the year. Purchasing aircraft requires a significant upfront cash investment and therefore reduces free cash flow in the year the aircraft are acquired. However, management views these purchases as an attractive use of capital because owning more of the fleet should reduce aircraft ownership costs over time. In other words, Norwegian deliberately used some of its cash to strengthen the economics of the business rather than the decline being driven solely by weaker operations. Norwegian is also preparing for the arrival of new Boeing aircraft over the coming years. Aircraft purchases naturally make Norwegian a more capital intensive business and mean that free cash flow can fluctuate considerably depending on the timing of deliveries and payments. However, Norwegian has already prepaid a large portion of the required payments related to its Boeing order book, while remaining prepayments before 2028 are relatively limited. This should reduce some of the near term pressure on cash flow. The newer aircraft should also gradually improve the economics of the fleet because they are more fuel efficient and should have lower maintenance requirements than older aircraft. If Norwegian can combine these benefits with high aircraft utilization, the investments being made today could support stronger cash generation over the longer term. Looking ahead, I expect Norwegian to remain free cash flow positive under normal operating conditions, although investors should not expect free cash flow to increase smoothly every year. Airlines are capital intensive businesses, and Norwegian will continue spending significant amounts on aircraft, maintenance, technology, and other investments. The timing of aircraft purchases alone can cause large movements in free cash flow from one year to another. Cash generation is also highly seasonal because customers often purchase summer tickets months before they actually travel, meaning Norwegian typically builds cash ahead of the important summer season and then uses part of that cash later in the year. Fuel prices, ticket prices, passenger demand, and operational disruptions can also cause significant fluctuations. There are nevertheless several reasons why the underlying free cash flow generation could improve over time. Norwegian's current strategy is considerably more disciplined than the strategy it followed before its restructuring. The company is focused on profitable routes rather than aggressive expansion, while newer aircraft should gradually improve fuel efficiency and reduce operating costs. The integration of Widerøe provides further opportunities to reduce costs through procurement, shared facilities, organizational efficiencies, and other synergies. Widerøe itself has also been improving its profitability. If Norwegian can continue growing earnings while maintaining discipline around capacity and investments, more of the cash generated from operations should ultimately be available as free cash flow. Norwegian uses its free cash flow primarily to strengthen the business, invest in its fleet, reduce debt, and increasingly return capital to shareholders. Strengthening the balance sheet has been a major priority since the restructuring. In 2025, Norwegian repaid its remaining corporate debt and removed several legacy financial obligations, leaving the company with a much cleaner balance sheet. The company has also used cash to purchase aircraft that were previously leased, supporting its longer term ambition of owning a larger portion of the fleet and reducing ownership costs. At the same time, Norwegian has reached a point where it can once again return cash to shareholders through dividends. The company began paying dividends in 2025 and intends to maintain a dividend friendly approach while balancing shareholder distributions with the investments required by the business. This represents an important change from the years following the restructuring, when rebuilding the company's financial position understandably took priority. The free cash flow yield suggests that Norwegian is trading at a very attractive valuation. However, we will revisit the valuation later in the analysis.
Debt
Another important aspect to consider is debt. It is crucial to assess whether a business has a manageable level of debt that can be repaid within a three-year period, calculated by dividing total long-term debt by earnings. Upon analyzing Norwegian’s financials, the company currently has 1,4 years of earnings in debt, which is comfortably below the three-year threshold. Norwegian's debt position has improved significantly in recent years, particularly as management has focused on strengthening the balance sheet following the company's restructuring. During 2025, Norwegian repaid its remaining corporate debt and removed several financial obligations left over from the company's previous financial difficulties. As a result, management has described Norwegian as essentially debt-free apart from financing related to its aircraft and a small amount of debt within Widerøe. Most of Norwegian's remaining debt is related to financing its aircraft, which is a normal part of operating an airline and investing in its fleet. Norwegian has also built a strong cash position, further strengthening the balance sheet. The improved financial position is beginning to provide additional benefits. Management has noted that banks are now offering Norwegian financing on significantly more attractive terms than in the past, which should be particularly valuable as the company takes delivery of new aircraft in the coming years. Norwegian will therefore take on additional aircraft financing as it expands and renews its fleet, meaning debt may increase from current levels. However, this appears to be a deliberate part of the company's fleet strategy rather than a return to the excessive borrowing that characterized Norwegian before its restructuring.
Support the Blog
I want to keep the blog free and accessible for everyone. If you enjoy the content and would like to support it, you can buy me a cup of coffee through PayPal. Every little bit helps and is truly appreciated!

Risks
Macroeconomics and geopolitics is a risk for Norwegian because the airline industry is highly sensitive to economic conditions and global events that are outside the company's control. Air travel, particularly leisure travel, is largely a discretionary expense, meaning consumers can reduce or postpone trips when their financial situation becomes more challenging. This is particularly relevant for Norwegian because leisure travelers represent an important part of the company's customer base. Periods of high inflation, high interest rates, rising unemployment, or weaker economic growth can leave households with less money available for vacations and other discretionary spending. Business travel can also decline when companies become more cautious about spending. Even if passengers continue traveling, difficult economic conditions can make them more price sensitive, which can limit Norwegian's ability to increase ticket prices. This is important because Norwegian may sometimes need to raise fares to compensate for higher costs. Management experienced this when higher fuel prices led Norwegian to increase ticket prices. However, the higher fares did not hold as well as management had hoped because passenger demand did not fully support them. This illustrates one of the challenges of the airline business. Costs can increase quickly, while Norwegian cannot always pass the entire increase on to customers without affecting demand. Macroeconomic conditions can also increase Norwegian's costs directly. Inflation can lead to higher salaries, maintenance expenses, airport charges, and other operating costs. Personnel costs are particularly important because Norwegian employs thousands of pilots, cabin crew, and other employees, and salary increases can have a meaningful impact on expenses. Norwegian also regularly negotiates agreements with employees, including pilots and technicians, creating the possibility of further wage increases. Airport charges represent another source of cost pressure. Norwegian has experienced significant increases in airport and air traffic control charges in recent years, particularly in Norway. Management has warned that continually increasing these fees could eventually make certain routes less attractive. Norwegian has some flexibility because it can move aircraft between countries and routes, but doing so may mean reducing capacity in markets where costs have become too high. Fuel prices represent one of the largest macroeconomic risks because jet fuel is one of Norwegian's most significant expenses. Fuel prices can move rapidly based on global oil prices, economic conditions, supply disruptions, and geopolitical events. Norwegian can protect itself against some of these movements by locking in fuel prices in advance, but this protection is only partial and temporary. A sharp increase in fuel prices can therefore quickly increase costs and reduce profitability if Norwegian cannot compensate by raising ticket prices. Foreign exchange movements add another layer of uncertainty because important airline expenses, including fuel and aircraft related costs, are often priced in U.S. dollars, while much of Norwegian's revenue is generated in Nordic and European currencies. A stronger U.S. dollar can therefore make these expenses more costly. Geopolitical conflicts can make all of these challenges more severe. The war in Ukraine and tensions in the Middle East demonstrate how quickly geopolitical events can affect aviation. Conflicts can push oil prices higher, close airspace, disrupt supply chains, reduce demand for certain destinations, and force airlines to cancel or change routes. Norwegian has already experienced this directly in the Middle East. The company canceled its Dubai services and postponed planned flights to Tel Aviv and Beirut because of the geopolitical situation. Norwegian was able to move this capacity to popular European destinations, particularly around the Mediterranean, where demand remained strong. This flexibility reduces the impact of individual route disruptions, but a larger or more widespread conflict could be considerably more difficult to manage. The Middle East is particularly important because escalating conflicts in the region can disrupt global energy markets and cause jet fuel prices to increase sharply even if Norwegian operates relatively few flights there. Trade tensions and disruptions to global supply chains could also affect Norwegian indirectly by increasing the cost or delaying the delivery of aircraft, engines, spare parts, and other equipment. This is especially relevant as Norwegian renews and expands its fleet over the coming years.
Regulations is a risk for Norwegian because the airline industry is heavily regulated, and changes in environmental rules, taxes, passenger rights, and other regulations can significantly increase the cost of operating an airline. This is particularly important for Norwegian because the company competes partly by maintaining a low cost base and offering affordable fares. If governments introduce additional costs, Norwegian must either absorb them, which reduces profitability, or increase ticket prices, which could weaken demand. One of the most important regulatory risks is the increasing environmental regulation of aviation in Europe. Airlines operating within Europe are covered by the European Union Emissions Trading System, which requires them to account for the carbon emissions generated by their flights. Airlines historically received some carbon allowances for free, but these free allowances are being phased out, requiring Norwegian to purchase more allowances and increasing the cost associated with every flight. Management has noted that these costs are becoming an increasingly significant part of Norwegian's fuel expenses. The price of carbon allowances can also fluctuate considerably, creating additional uncertainty. Norwegian generally purchases allowances as the emissions occur, but changes in allowance prices can still affect costs and profitability. Environmental regulation is also increasing through requirements for sustainable aviation fuel. Airlines operating in Europe are gradually being required to use a larger proportion of sustainable aviation fuel, which is currently considerably more expensive than conventional jet fuel. These requirements are expected to become stricter over time, meaning Norwegian could face steadily increasing fuel costs even if conventional jet fuel prices remain unchanged. While Norwegian can attempt to pass these costs on through higher ticket prices, doing so is not always easy in a highly competitive industry where customers can quickly compare fares between airlines. Government taxes and airport charges represent another regulatory risk. European countries can introduce or increase taxes on airline passengers as part of environmental or fiscal policies, making flying more expensive. These taxes can be particularly challenging for low cost airlines because a fixed tax represents a larger percentage of a cheap ticket than an expensive one. Higher taxes can therefore reduce the affordability advantage that Norwegian relies on to stimulate demand. Norwegian has also experienced significant increases in airport and air traffic control charges. While these are not always directly controlled by governments, many airports and air traffic infrastructure providers are publicly owned or heavily regulated. Management has been particularly critical of rising charges in Norway and has warned that excessive increases could make certain routes less attractive. Norwegian can respond by moving aircraft to markets where the economics are better, but this does not eliminate the underlying risk. Passenger protection regulations can also create additional costs. Under European rules, airlines may be required to compensate passengers for significant delays and cancellations, as well as provide meals, accommodation, and alternative transportation in certain situations. These protections are beneficial for passengers but can create substantial costs for airlines when operations are disrupted. The financial impact can become particularly significant during periods of widespread cancellations or operational problems because compensation may be required for large numbers of passengers at the same time. Changes in how these rules are interpreted could further increase Norwegian's obligations in the future. Regulations can also create unexpected financial consequences, as Norwegian's recent dispute concerning its historical EU emissions obligations demonstrates. The case related to obligations from the period when Norwegian was undergoing its financial reconstruction. Norwegian initially won the case but later lost on appeal, while the Supreme Court declined to hear its further appeal. This resulted in a significant one time expense for the company despite management and its legal advisers believing Norwegian had been unable to meet the obligation during its reconstruction. While this particular issue relates to Norwegian's past and should not be considered a recurring expense, it demonstrates how regulatory obligations and legal interpretations can create significant unexpected costs. Looking ahead, environmental regulation is probably the most important regulatory risk for Norwegian. European governments have ambitious targets for reducing aviation emissions, and airlines are likely to face progressively higher costs related to carbon emissions and sustainable aviation fuel.
Competition is a risk for Norwegian because the airline industry is highly competitive, and passengers can easily compare prices and schedules across different airlines before booking a flight. For many travelers, particularly leisure travelers, price is one of the most important factors when choosing an airline. This means that if another airline offers a cheaper ticket at a similar departure time, Norwegian may need to lower its fares to remain competitive. Airlines also have high fixed costs because aircraft, employees, airport facilities, and many other expenses must be paid regardless of how full the planes are. This creates a strong incentive for airlines to fill as many seats as possible, sometimes leading them to reduce ticket prices when there is too much capacity in the market. As a result, even relatively small changes in competition can have a meaningful impact on ticket prices and profitability. Norwegian's most important competitor in the Nordic market is SAS, and management describes the competition between the two airlines as a constant fight. The companies compete on many of the same routes, particularly between the Nordic capitals and on popular European destinations. SAS has increasingly focused its operations around Copenhagen, strengthening Copenhagen's role as its main international hub. A stronger SAS presence in Copenhagen could create additional competitive pressure for Norwegian, particularly if SAS adds routes, frequencies, or capacity. SAS also has advantages as a network airline and member of the SkyTeam alliance, allowing it to offer passengers connections to a much larger international network. This can be particularly attractive to business travelers and customers traveling beyond Norwegian's own network. Norwegian also faces competition from other European low cost airlines such as Ryanair, easyJet, and Wizz Air. These airlines have large fleets and low cost structures, giving them the ability to enter markets where they see attractive opportunities. Even if they do not currently compete heavily with Norwegian across its entire Nordic network, they can add capacity to individual routes and put pressure on ticket prices. This is important because an airline does not need to challenge Norwegian across the whole Nordic market to affect its profitability. If a competitor adds a significant number of seats to a popular destination, Norwegian may have to lower its fares to protect passenger volumes. Competition can also change relatively quickly because airlines can move aircraft between markets. Norwegian experienced this during the pandemic, when several competitors entered the Nordic market. Some have since exited, while other airlines have increased their presence. Management currently describes the competitive landscape in Norwegian's main markets as relatively stable, but there is no guarantee that it will remain this way. If the Nordic aviation market becomes more attractive or profitable, existing competitors could increase capacity and new competitors could enter. Competition is particularly dangerous when airlines add too much capacity because the number of available seats can grow faster than passenger demand. Airlines may then compete more aggressively on price to fill their aircraft, putting pressure on fares and margins across the industry. Norwegian's own growth can also trigger competitive responses. If Norwegian adds flights to a profitable route, competitors may respond by increasing their own capacity or lowering fares to defend their market position. Widerøe also faces competition within the Norwegian domestic market, although its strong regional network and ability to operate at many smaller airports provide some protection. On larger domestic routes, however, the Norwegian Group still competes directly with other airlines, particularly SAS. Loyalty programs represent another competitive factor. Norwegian Reward and Spenn compete for customer loyalty against programs such as SAS EuroBonus, and frequent travelers may choose an airline partly based on the rewards and benefits they receive. SAS's membership in SkyTeam can strengthen this offering because passengers can earn and use benefits across a large international airline network.
Reasons to invest
Passenger growth is a reason to invest in Norwegian because the company has experienced growing passenger demand across both Norwegian and Widerøe, providing an important foundation for future revenue and earnings growth. This is particularly important in the airline industry because many costs are relatively fixed once a flight is scheduled. Whether an aircraft is partly full or almost completely full, Norwegian still needs the aircraft, pilots, cabin crew, and airport services required to operate the flight. Carrying more passengers and filling a greater percentage of available seats can therefore have a meaningful positive effect on profitability. Importantly, Norwegian's recent passenger growth has not simply been achieved by adding large amounts of capacity. Management has become more disciplined about matching capacity with expected demand, reducing the number of available seats during weaker periods while increasing capacity when demand is stronger. This has resulted in higher load factors, meaning Norwegian is filling a greater percentage of its available seats. At the same time, ticket yields have improved, which is encouraging because it suggests that Norwegian has been able to attract more passengers without relying on lower ticket prices to fill its aircraft. Widerøe has also contributed positively to passenger growth and has reached record passenger levels since becoming part of the Norwegian Group. Widerøe gives the group exposure to a somewhat different passenger base because its regional network connects many smaller Norwegian cities with larger airports. This complements Norwegian's broader domestic and European network and creates opportunities to move passengers between the two airlines. Connecting traffic between Norwegian and Widerøe has already been growing, and the introduction of a new distribution platform should make it easier for passengers to book journeys involving both airlines. This could further increase passenger traffic by allowing Widerøe to feed passengers from smaller regional destinations into Norwegian's larger network and vice versa. Another potential source of passenger growth is the corporate market. While business travel in Norway remains below the levels seen before the pandemic, Norwegian has been increasing both its number of corporate passengers and its corporate revenue, indicating that the company is gaining market share. Norwegian has signed agreements with a growing number of businesses and public organizations, while management has indicated that some large corporate customers are increasingly choosing Norwegian for a larger share of their travel. Corporate passengers are particularly attractive because they generally pay higher fares and travel more consistently throughout the year than leisure passengers. Increasing Norwegian's share of this market could therefore support passenger growth while also reducing some of the seasonality of the business. Widerøe strengthens this opportunity because its regional network is particularly important for business travel within Norway. Customer satisfaction could also support continued passenger growth. Norwegian has experienced a significant improvement in its Net Promoter Score, indicating that customers have become more satisfied and more likely to recommend the airline. Operational performance is an important part of this development. Norwegian has consistently emphasized punctuality and avoiding cancellations and has ranked among the more punctual airlines in Europe. This matters because arriving on time and knowing that a scheduled flight is likely to operate are important factors when customers choose an airline. Strong operational performance could therefore encourage existing passengers to continue choosing Norwegian while strengthening the company's reputation among new customers. Norwegian Reward and Spenn could further support passenger growth by increasing customer loyalty. Spenn is developing into a broader Nordic loyalty ecosystem involving Norwegian, Strawberry, and Reitan Retail, allowing customers to earn and use rewards across flights, hotels, grocery stores, convenience stores, and other businesses. The addition of Reitan significantly increases the number of everyday interactions customers can have with Spenn, which could make the loyalty program more relevant even when customers are not traveling. If Norwegian can successfully turn this broader ecosystem into stronger customer loyalty, members may become more likely to choose Norwegian when booking flights. There are also opportunities for passenger growth in Nordic markets that have not fully recovered from the pandemic. Sweden is particularly interesting because domestic air travel remains significantly below its previous level. Norwegian has been strengthening its position in the Swedish market, while management also sees potential opportunities for Widerøe if regional aviation develops in a similar direction to Norway. A recovery in Swedish air travel could therefore provide another source of passenger growth over the longer term.
Fleet renewal is a reason to invest in Norwegian because the company is in the process of modernizing its aircraft fleet with new Boeing 737 MAX 8 aircraft, which should gradually improve efficiency, lower costs, and support profitable growth. Norwegian has a large order of new aircraft that will be delivered gradually through 2031, allowing the company to replace older aircraft while expanding the fleet at a controlled pace. This is important because aircraft are one of the largest investments for any airline, and the efficiency of the fleet has a significant impact on long term profitability. The Boeing 737 MAX 8 consumes around 14% to 15% less fuel than the older Boeing 737 NG aircraft it replaces. Fuel is one of Norwegian's largest operating expenses, meaning even relatively small improvements in fuel efficiency can have a meaningful impact on costs when multiplied across thousands of flights. A more fuel efficient fleet also reduces carbon emissions per passenger, which is becoming increasingly important as European airlines face higher costs related to carbon emissions and environmental regulations. Newer aircraft should therefore help Norwegian partly offset some of the increasing environmental costs facing the airline industry. The benefits extend beyond fuel consumption. New aircraft generally require less maintenance than older aircraft and provide Norwegian with a more reliable and efficient fleet. They also offer a quieter and more comfortable experience for passengers and employees. This could support Norwegian's broader focus on customer satisfaction and operational reliability while reducing the risk of disruptions caused by older aircraft. Another important part of Norwegian's fleet strategy is the company's intention to own a larger percentage of its aircraft rather than relying as heavily on leasing. Historically, Norwegian leased a large part of its fleet, meaning it had to make ongoing payments to aircraft leasing companies. Management believes that owning aircraft can be cheaper over the long term when attractive financing is available. Norwegian has already purchased several aircraft that it previously leased and has experienced recurring cost savings from doing so. Management has indicated that Norwegian could eventually own more than half of its fleet as the new Boeing aircraft arrive. This represents an important change from the past and could gradually reduce aircraft ownership costs. Norwegian's stronger financial position makes this strategy more achievable. Management has reported strong interest from banks and other financing providers that are willing to finance the new aircraft on attractive terms. This is significantly different from Norwegian's position before its restructuring, when the company had a much weaker balance sheet and aggressive fleet expansion contributed to its financial difficulties. The current strategy appears more disciplined, with management balancing the benefits of ownership against the amount of cash required to purchase aircraft. Norwegian has also already made a significant portion of the required prepayments on its Boeing order, reducing some of the near term cash requirements associated with the deliveries. The timing of the aircraft deliveries is another important part of the investment case. Rather than rapidly expanding the fleet regardless of market conditions, Norwegian has structured deliveries so that new aircraft can gradually replace leased aircraft as those leases expire. This allows the company to modernize the fleet without necessarily creating excessive capacity. At the same time, Norwegian retains flexibility because many of its older aircraft are leased. If passenger demand is weaker than expected, Norwegian can allow some leases to expire as new aircraft arrive. If demand is stronger and attractive growth opportunities emerge, the company can extend leases and keep those aircraft for longer, allowing the fleet to grow faster. This gives Norwegian the ability to adjust its fleet according to market conditions instead of committing to aggressive growth years in advance. This flexibility is particularly valuable in the airline industry because passenger demand can change quickly depending on economic conditions, competition, fuel prices, and geopolitical events. The new aircraft can also support continued expansion of Norwegian's route network. Norwegian already operates an extensive network of direct routes between the Nordic countries and destinations across Europe, and additional aircraft provide opportunities to add new destinations and increase frequencies on routes where demand is strong. However, management has emphasized that fleet growth should follow profitable market opportunities rather than growth being an objective by itself. This is an important distinction given Norwegian's history. Before its restructuring, rapid fleet and network expansion contributed to excessive debt and financial problems. The current fleet strategy is considerably more measured, with management planning moderate underlying growth while retaining the option to grow faster if market conditions justify it. There is also a strategic advantage to having secured aircraft deliveries years in advance. The supply of new commercial aircraft is constrained, and both Boeing and Airbus have large order books extending several years into the future. Airlines that want significant numbers of new aircraft cannot necessarily obtain them quickly. Norwegian's existing order therefore provides visibility over its fleet renewal and access to modern aircraft without having to compete for all of its future requirements in an increasingly constrained market.
Expansion into packaged holidays is a reason to invest in Norwegian because the planned acquisition of Nordic Leisure Travel Group, or NLTG, would allow Norwegian to expand beyond simply selling airline tickets and capture a larger share of what customers spend on their holidays. NLTG is a leading Nordic leisure travel company with well known brands such as Ving, Spies, Tjäreborg, Globetrotter, Sunclass Airlines, and a portfolio of concept hotels. By combining Norwegian's airline network with NLTG's hotels, holiday packages, digital platform, and tour operator experience, the group would be able to offer customers a much broader travel product that includes flights, accommodation, activities, and other holiday services. This is attractive because Norwegian already carries millions of leisure passengers every year, meaning the company does not necessarily need to create an entirely new customer base. Instead, it can try to sell more products to passengers who are already using Norwegian to travel to popular holiday destinations. This could increase the amount of revenue Norwegian earns from each customer and reduce its dependence on the airline ticket itself. The strategic fit is especially strong because Norwegian already has a large presence on many of the destinations that are important to Nordic holidaymakers, particularly in Southern Europe. NLTG can use Norwegian's network to offer customers more departure options and greater flexibility, while Norwegian can use NLTG's hotel portfolio and holiday brands to create a more complete travel offering. Over time, Norwegian could also help NLTG expand its concept hotels into destinations where Norwegian already has significant passenger traffic. This creates the potential for a more integrated travel model where Norwegian can generate value both from transporting the customer and from a larger portion of the holiday itself. NLTG's concept hotels are particularly interesting because they represent an important part of the company's profitability. These hotels account for a smaller portion of NLTG's total guest volume but generate a much larger share of its profit. Expanding the number of concept hotels in destinations where Norwegian already has a strong presence could therefore become an important growth opportunity. Instead of only benefiting from increased passenger traffic to a destination, Norwegian could also participate in the value created when those passengers stay at hotels within the group. Another important opportunity comes from combining Norwegian and Sunclass Airlines. Sunclass operates charter flights for NLTG, while Norwegian operates a much larger scheduled network. Management believes there are opportunities to improve how the two airlines use aircraft and crews, particularly by reducing flights where aircraft have to be moved without carrying a normal passenger load. Better coordination between the airlines could improve aircraft utilization and lower costs. The larger combined group could also negotiate better terms when purchasing fuel, maintenance, airport services, insurance, aircraft leases, and other services because it would be buying at greater scale. Norwegian has already gained experience with this type of integration through Widerøe, where the company has been working to reduce overlapping costs and improve cooperation between the two airlines. NLTG could also make Norwegian's earnings less dependent on the seasonal pattern of traditional airline travel. Norwegian's business is strongly weighted toward the summer months, while NLTG has somewhat less seasonality. Package holiday customers also often book further in advance than passengers buying only airline tickets, potentially giving Norwegian better visibility into future demand. Management sees particular opportunities during the periods between the peak summer and winter seasons, when hotels and aircraft might otherwise be less fully utilized. If Norwegian can use packaged holidays to stimulate demand during these periods, the acquisition could improve the utilization of both aircraft and hotels across more of the year. The combination could also strengthen Norwegian's digital and loyalty offering. NLTG has invested heavily in its digital booking platform, while Norwegian has been expanding Norwegian Reward and Spenn. Combining these platforms could make it easier to sell flights, hotels, activities, and other travel products to the same customer. A passenger who books a Norwegian flight could be offered accommodation through NLTG, while an NLTG customer could gain easier access to Norwegian's extensive Nordic and European route network. Spenn could potentially strengthen this relationship further by rewarding customers across more parts of their travel experience. This could increase customer loyalty and encourage travelers to keep more of their holiday spending within the Norwegian group. The acquisition would also diversify Norwegian's business. Airlines can experience significant swings in profitability because of fuel prices, competition, weather, economic conditions, and changes in passenger demand. Adding hotels, tour operations, travel retail, and package holidays would give Norwegian additional sources of revenue and earnings. NLTG itself has a long history in Nordic leisure travel and brings experienced management with knowledge of hotels and tour operations that Norwegian does not currently have. This is important because Norwegian is not attempting to build a hotel and package holiday business from scratch. Instead, it is acquiring an established operator with recognizable brands, an existing customer base, its own hotels, an airline, and a developed digital platform. The broader Nordic leisure travel market also offers attractive long term potential. Nordic consumers have traditionally spent heavily on international holidays, particularly to Southern Europe, and demand for leisure travel has continued to grow. Norwegian is already one of the largest providers of flights from the Nordics to these destinations, while NLTG is one of the region's leading package holiday providers. Combining the two could therefore create a stronger position across the entire leisure travel journey.
Unlock Exclusive Seeking Alpha Discounts – Level Up Your Investing With Zero Risk
If you’ve been thinking about improving your investing process, this is the easiest way to start. These offers are only available through my links, and the Premium plan even comes with a 100% risk-free 7-day trial. Try everything for a week, and if it’s not for you, just cancel. You lose nothing.
1) Seeking Alpha Premium — Try It Free for 7 Days
Access the tools I personally use every day:
• Earnings transcripts
• Stock screeners
• Deep-dive analysis
• Portfolio tracking
• Market news with context that actually matters
Special Price: $269/year (normally $299) + 7-day free trial (for new users only)
Try Premium Free for 7 Days → HERE
(Explore everything — cancel anytime during the trial and pay $0.)
2) Alpha Picks — Proven Stock Ideas
This stock-picking service has delivered +287% returns vs. the S&P 500’s +77% (July 2022–Nov 2025).Great for investors who want curated, long-term picks backed by data.
Special Price: $449/year (normally $499)
Get Alpha Picks → HERE
(Although Alpha Picks doesn’t offer a free trial, its historical outperformance means the subscription can often pay for itself quickly if results persist. For many investors, the potential return far outweighs the upfront cost).
3) Premium + Alpha Picks Bundle — Best Value
Get both services together and save $159.Perfect if you want both broad tools and high-conviction stock ideas.
Special Price: $639/year (normally $798)
Get the Bundle → HERE
(This bundle doesn’t include a free trial, but it gives you both services at a $159 discount. You get Premium’s in-depth research plus Alpha Picks’ high-performing recommendations, making it the most comprehensive option for serious investors.)
Valuation
Now it is time to calculate the share price. I perform three different calculations that I learned at a Phil Town seminar. If you want to make the calculations yourself for this or other stocks, you can do so through the tools page on my website, where you have access to all three calculators for free.
The first is called the Margin of Safety price, which is calculated based on earnings per share (EPS), estimated future EPS growth, and estimated future price-to-earnings ratio (P/E). The minimum acceptable rate of return is 15%. I chose to use an EPS of 2,49, which is from year 2025. I have selected a projected future EPS growth rate of 10%. Finbox expects EPS to grow by 9,9% a year in the next five years. Additionally, I have selected a projected future P/E ratio of 20, which is twice the growth rate. This decision is based on Norwegian's historically higher price-to-earnings (P/E) ratio. Finally, our minimum acceptable rate of return has already been established at 15%. After performing the calculations, we determined the sticker price (also known as fair value or intrinsic value) to be NOK 31,96. We want to have a margin of safety of 50%, so we will divide it by 2. This means that we want to buy Norwegian at a price of NOK 15,96 (or lower, obviously) if we use the Margin of Safety price.
The second calculation is known as the Ten Cap price. The rate of return that a company owner (or stockholder) receives on the purchase price of the company essentially represents its return on investment. The minimum annual return should be at least 10%, which I calculate as follows: The operating cash flow last year was 7.840, and capital expenditures were 5410. I attempted to analyze their annual report to calculate the percentage of capital expenditures allocated to maintenance. I couldn't find it, but as a rule of thumb, you can expect that 70% of the capital expenditures will be allocated to maintenance purposes. This means that we will use 3.787 in our calculations. The tax provision was 308. We have 1.052 outstanding shares. Hence, the calculation will be as follows: (7.840 – 3.787 + 308) / 1.052 x 10 = NOK 41,45 in Ten Cap price.
The final calculation is called the Payback Time price. It is a calculation based on the free cash flow per share. With Norwegian's Free Cash Flow Per Share at NOK 2,31 and a growth rate of 10%, if you want to recoup your investment in 8 years, the Payback Time price is NOK 29,06.
Conclusion
I believe Norwegian is an intriguing company with a strong management team that has transformed the business since the restructuring. The company has built its moat through its Nordic network, scale, cost position, brand and loyalty ecosystem, and the complementary regional infrastructure provided by Widerøe. Norwegian's ROIC has historically been weak, reflecting both the capital intensive nature of the airline industry and the company's former aggressive growth strategy. However, the improvement since the 2021 restructuring is encouraging, with ROIC reaching 11,6% in 2025, although Norwegian still needs to demonstrate that it can sustain returns around or above 10% across an entire aviation cycle. Free cash flow has also improved significantly since the restructuring, with the company generating positive free cash flow every year since 2021. While cash flow will remain volatile because of aircraft investments and the capital intensive nature of the industry, the more disciplined strategy, improving fleet efficiency, and lower aircraft ownership costs should support stronger underlying cash generation over time. There are still several risks investors should consider. Macroeconomics and geopolitics are risks because weaker economic conditions can reduce travel demand, while inflation, higher fuel prices, wage increases, and unfavorable currency movements can simultaneously increase costs. Geopolitical conflicts can further pressure profitability by increasing fuel prices, disrupting supply chains, closing airspace, and forcing Norwegian to cancel or relocate routes. Regulations are another risk because stricter environmental rules, higher taxes, airport charges, and passenger protection requirements can increase operating costs. Environmental regulations are particularly important, as rising carbon costs and requirements to use more expensive sustainable aviation fuel are likely to increase costs over time. Competition is also a risk because passengers can easily compare fares and switch between airlines, while competitors such as SAS and other European low cost carriers can add capacity and put pressure on ticket prices. If competition intensifies, Norwegian may need to lower fares to maintain passenger volumes, which could pressure margins and profitability. Despite these risks, there are several reasons to invest in Norwegian. Passenger growth is one of them because growing demand, higher load factors, and improving ticket yields allow the company to generate more revenue and profit from its aircraft and infrastructure. Further growth could be supported by Widerøe's regional network, increasing corporate travel, improving customer loyalty, and opportunities in underpenetrated Nordic markets. Fleet renewal is another reason to invest, as new Boeing 737 MAX 8 aircraft should lower fuel, maintenance, and ownership costs while improving operational efficiency. The flexible delivery schedule also allows Norwegian to replace older aircraft while adjusting fleet growth according to demand, supporting more disciplined and profitable growth. Finally, the expansion into packaged holidays through the planned NLTG acquisition could allow Norwegian to capture a larger share of its passengers' holiday spending through hotels, packages, and other travel services. The combination could also diversify earnings, improve aircraft utilization, reduce costs through synergies, and create new growth opportunities by expanding NLTG's profitable concept hotels into destinations where Norwegian already has a strong presence. Overall, I believe there are many things to like about Norwegian and the direction in which management is taking the company. However, I personally do not want exposure to the airline industry because of its capital intensive and cyclical nature. For investors who are comfortable with these characteristics, I believe Norwegian could be an interesting investment below my margin of safety price of NOK 15.
Follow my investment journey
I hope you enjoyed this analysis. I regularly publish in depth company analyses on InvestSeekers and share updates on the companies I follow.
If you would like to see what I currently invest in, I publicly share my portfolio and any changes I make over time. You can also learn how to follow or copy my portfolio through the investment platform I use.
Stay updated
If you enjoy my company analyses, you can sign up for my free newsletter to receive my latest analyses, investment ideas, and other updates directly in your inbox. Subscribers may also receive selected content before it is published publicly on InvestSeekers. Simply scroll to the bottom of this page and sign up.
Watch on YouTube
If you prefer a faster and more visual way to understand a company, I also publish videos on YouTube covering Nordic companies that receive relatively little coverage in English. Each video provides an understandable overview of the business, financials, risks, reasons to invest, and valuation.
Follow me on X
I also share more frequent investment updates on X, including company news, new analyses, and changes I make to my portfolio.
A cause I support
If you found my analysis valuable and would like to support a good cause, I encourage you to consider making a small donation to ADEPAC. It is a charity I know firsthand, and I have seen the valuable work they do despite having very limited resources.
Even a small donation can make a difference.


Comments