ChemoMetec: A Niche Player with High Growth Potential
ChemoMetec is a Danish life science technology company specializing in cell counting and analysis equipment used by pharmaceutical companies, biotechnology companies, and research institutions. The company is particularly well established within cell and gene therapy, where its instruments help customers measure cell concentration and viability throughout research, development, and manufacturing. With a growing presence in bioprocessing, a new generation of XcytoMatic instruments, and an increasing focus on automation, software, and partnerships, ChemoMetec aims to become more deeply integrated into pharmaceutical manufacturing workflows. The question remains: Does this Danish life science company deserve a spot in your portfolio?
This is not financial advice. I am not a financial advisor, and I publish these analyses to document my own research and share my thoughts with readers and followers. If you are considering investing in any of the companies or ideas discussed, you should always do your own research and, if necessary, consult a qualified financial professional. All investing involves risk, and you may lose some or all of the money you invest.
For full disclosure, I do not own shares in ChemoMetec at the time of writing this analysis. I publicly share my investment portfolio, including all of my current holdings and changes I make over time. If you are interested in seeing what I currently invest in and learning how you can follow or copy my portfolio, you can read more here.
The Business
ChemoMetec is a Danish life science technology company that develops, manufactures, and sells instruments used to count and analyze cells. Cell counting may sound like a relatively simple task, but it is an important part of biological research and the development and manufacturing of many modern medicines. Researchers and pharmaceutical companies need to know how many cells are present in a sample, how many of those cells are alive, and whether the cells have the characteristics required for the next step of a research or manufacturing process. Accurate and consistent measurements are particularly important when cells themselves form part of a therapy, as is the case with cell and gene therapies. ChemoMetec has built a strong position in this specialized market by developing automated cell counting and analysis systems that replace more manual and potentially less consistent methods. Its instruments combine fluorescence microscopy, cameras, and proprietary image analysis software to automatically analyze prepared cell samples. This allows customers to count large numbers of cells quickly and consistently while reducing the influence of the individual laboratory technician performing the analysis. The company’s largest business area consists of what it calls the LCB market, which includes life science research, cell and gene therapy, and bioprocessing. Together, these areas accounted for approximately 95% of ChemoMetec’s revenue in the 2025/26 financial year. The remaining business includes more specialized applications such as production and quality control of animal semen, beer, and milk. ChemoMetec sells its products globally, with the United States and Canada representing its largest geographical market, followed by Europe. Life science research covers the earlier stages of biological research performed by universities, research institutions, biotechnology companies, and pharmaceutical companies. Scientists may use ChemoMetec instruments when studying cells, developing new medicines, screening cell cultures, or conducting experiments that require reliable measurements of cell concentration and viability. Although these applications can eventually lead to commercial medicines, the instruments are initially used primarily as research tools. Cell and gene therapy is particularly important to ChemoMetec. Unlike traditional medicines that are manufactured from chemical compounds or biological molecules, some cell therapies use living cells as the medicine itself. CAR-T cancer therapy is a good example. In CAR-T treatment, immune cells are collected from a patient, modified so they can recognize cancer cells, multiplied outside the body, tested, and eventually returned to the patient. Cell concentration and viability must be monitored throughout this manufacturing process, making reliable cell counting an important part of producing the final therapy. ChemoMetec’s NucleoCounter technology is used for applications including CAR-T manufacturing, and its systems are designed to provide consistent measurements across different operators, instruments, and production locations. Bioprocessing represents another important market and an increasingly significant growth opportunity for ChemoMetec. Bioprocessing broadly refers to the use of living cells or biological organisms to manufacture medicines. Pharmaceutical companies grow cells inside controlled production environments and continually monitor these cell cultures to ensure that the manufacturing process develops as expected. Cell concentration and viability therefore need to be measured repeatedly as production moves from laboratory development to larger commercial manufacturing volumes. There is considerable overlap between cell and gene therapy and bioprocessing because both involve biological production processes. One of the most important developments across both markets is increasing automation. Pharmaceutical companies are trying to reduce manual work, improve consistency, increase production capacity, and ultimately lower the cost of manufacturing biological medicines. ChemoMetec is adapting its product portfolio to this development by moving beyond stand-alone cell counters toward instruments that can become integrated components of automated production systems. The company’s traditional NucleoCounter instruments are built around fluorescence-based image cytometry. A prepared cell sample is inserted into the instrument, images are captured, and ChemoMetec’s proprietary software automatically analyzes the cells. Instruments such as the NC-202 and newer NC-203 are designed to provide standardized measurements while reducing manual steps that can introduce variation between operators. The systems can also be configured for regulated manufacturing environments, including workflows subject to Good Manufacturing Practice requirements and FDA requirements concerning electronic records and signatures. ChemoMetec has historically complemented these instruments with proprietary consumables. Its NucleoCounter systems use specialized disposable cassettes containing the components required to prepare and analyze samples. These cassettes simplify the workflow, reduce pipetting and handling errors, and help standardize measurements. Once customers have installed a ChemoMetec instrument, continued use therefore generates demand for associated consumables. This gives the company an attractive combination of instrument sales and recurring revenue from the installed base. Services provide another source of recurring revenue through installation, servicing, qualification, software updates, technical assistance, and support with validation. However, ChemoMetec’s business model is gradually evolving. Its newer XcytoMatic platform has been designed specifically for customers that want greater automation and integration into pharmaceutical manufacturing workflows. The XM30 and XM40 can work with different sample formats and are designed to become part of broader automated systems rather than functioning solely as stand-alone laboratory instruments. This is important because customers increasingly want cell counting to happen automatically as part of the manufacturing process instead of requiring an employee to manually take a sample, prepare it, measure it, and enter the resulting data into another system. ChemoMetec is therefore increasingly developing not just cell counters but integrated analytical solutions. Software is becoming more important as the company develops systems capable of communicating with other laboratory and production equipment. ChemoMetec controls most of the important parts of its value chain. Product and software development are primarily managed from Denmark, while all instruments are manufactured by the company. External suppliers provide certain components, but important activities such as assembly, calibration, testing, and quality control are performed internally. Consumables such as cassettes are also manufactured at ChemoMetec’s facilities, giving the company significant control over the quality and consistency of products that customers depend on in regulated laboratory and manufacturing environments. Selling these products requires considerably more technical knowledge than selling conventional laboratory equipment. ChemoMetec therefore operates specialized sales and support organizations, particularly in the United States and Europe, while using distributors in parts of Asia. Employees need to understand not only the instruments but also the biological processes in which customers use them. The relationship often continues after the initial sale through installation, training, validation assistance, servicing, software updates, and technical support. This direct relationship with customers also feeds back into product development. ChemoMetec works closely with pharmaceutical and biotechnology companies to understand how their production processes are changing and what new analytical capabilities they require. This has become increasingly important as the industry moves toward automated manufacturing, where instruments need to communicate with other equipment and fit into highly specialized customer workflows. ChemoMetec’s competitive moat is primarily built on its specialized technology, integration into customers’ workflows, regulatory validation, customer relationships, and the high cost and inconvenience of changing analytical methods once they have become established. Patents and proprietary consumables reinforce this position, but arguably the most important advantage is that ChemoMetec’s instruments can become embedded in critical processes where customers place a very high value on consistency and reliability. research can theoretically be replaced relatively easily. The situation changes when the same analytical method becomes part of a validated manufacturing process for a medicine. Pharmaceutical companies operating under Good Manufacturing Practice requirements need to demonstrate that their processes and analytical methods consistently perform as intended. ChemoMetec itself offers qualification services and documentation designed to help customers use its instruments in regulated environments. Changing an instrument in such an environment is therefore not simply a matter of buying a competing machine. The customer may need to demonstrate that the replacement produces reliable and comparable results, update procedures and documentation, train employees, integrate the new equipment with existing software and production systems, and perform additional validation work. ChemoMetec has stated that validation of its newer products can take considerable time and, at larger customers, may take several years. The disadvantage is that this slows adoption of new ChemoMetec products, but once an instrument has successfully completed the process, the same dynamic can make customers reluctant to replace it unnecessarily. The potential switching costs become particularly meaningful in cell and gene therapy. A company manufacturing a CAR-T therapy needs reliable measurements throughout a process involving living cells, where consistency between production runs is important. If an existing ChemoMetec system has already demonstrated that it produces reliable results and employees have built their procedures around it, switching to another analytical platform introduces additional work and operational risk without necessarily creating much economic value. Cell counting equipment represents only a small part of the overall cost and value of manufacturing an advanced therapy, reducing the incentive to switch merely to save money on the instrument itself. ChemoMetec’s position within cell and gene therapy strengthens this advantage. The company has established relationships with many of the world’s leading pharmaceutical and biotechnology companies and has built a particularly strong position in advanced cell therapies. This creates an important installed base as well as experience with the specific requirements of customers operating in highly regulated environments. Its technology has also been used in CAR-T manufacturing, where its systems can support multiple stages of the cell manufacturing process. The consumables model adds another layer to the moat. Traditional NucleoCounter instruments are designed around ChemoMetec’s proprietary cassette system. Once an instrument has been selected and incorporated into a customer’s workflow, the customer continues purchasing compatible cassettes as the instrument is used. This creates recurring revenue and means the economic value of a customer relationship can extend well beyond the initial instrument sale. Usage can also increase as a customer's activity increases. A successful therapy moving from clinical development toward larger-scale commercial production may require considerably more cell counting, which can translate into higher demand for consumables and services without ChemoMetec having to win the customer again. Technology and intellectual property provide additional protection. ChemoMetec has spent many years developing its fluorescence microscopy, imaging, sample handling, and software technologies and has consistently used patents to protect important parts of its platform. More importantly, the technology has been refined around a specific objective: making cell counting fast, accurate, reproducible, and easy to use. The value proposition is not simply that ChemoMetec can count cells. Many competing technologies can do that. The advantage is the ability to provide standardized measurements with relatively little operator dependence while fitting into demanding research and regulated manufacturing environments. The company’s specialized focus may itself be an advantage. ChemoMetec is small compared with many global life science equipment companies, but cell counting and analysis has been the core of the business since its establishment. Its development teams, sales specialists, application scientists, and customer support organization therefore have significant knowledge concentrated around a relatively narrow area. Close contact with customers allows ChemoMetec to understand changes in laboratory and production workflows and develop products specifically around those needs. Customer service reinforces this position. Pharmaceutical and biotechnology customers are not simply purchasing an instrument and being left to operate it independently. ChemoMetec can assist with installation, qualification, validation, servicing, software, integration, and technical problems. As its products become increasingly integrated into automated workflows, this expertise becomes even more important because ChemoMetec needs to understand how its equipment interacts with other parts of the customer’s production environment. Scale within its niche also creates advantages. ChemoMetec sells globally and has built direct commercial organizations in its most important Western markets. This gives the company a larger installed base, more customer feedback, and greater resources for product development and support than a small new entrant could easily replicate. At the same time, relationships with large pharmaceutical companies provide credibility when approaching additional customers. In a regulated industry where reliability matters, a long history of successful use by other pharmaceutical companies can reduce the perceived risk of adopting the technology. The emerging automation ecosystem could strengthen this advantage further. If XcytoMatic instruments become connected to other equipment inside bioprocessing facilities, switching may eventually involve more than replacing a cell counter. Customers could need to change interfaces, software connections, automated workflows, data handling, and validated procedures. Overall, the strength of ChemoMetec’s competitive position comes less from owning a cell counting technology that competitors cannot reproduce and more from the combination of specialized technology, regulatory validation, consistent analytical performance, customer relationships, proprietary products, and deep integration into critical pharmaceutical workflows. Once ChemoMetec becomes part of a validated manufacturing process, customers have relatively little incentive to replace a system that works reliably.
Management
Martin Helbo Behrens serves as the CEO of ChemoMetec, a role Martin Helbo Behrens assumed in March 2024 after previously serving as the company’s COO. Martin Helbo Behrens has spent the majority of his professional career at ChemoMetec and has developed experience across finance, operations, commercial development, and international expansion. This gives Martin Helbo Behrens extensive knowledge of the company’s products, customers, organization, and markets at a time when ChemoMetec is transitioning from its established NucleoCounter business toward a greater focus on automation, software, and integrated solutions for cell and gene therapy and bioprocessing. Martin Helbo Behrens originally joined ChemoMetec as part of Group Finance before relocating to the United States in 2021. Martin Helbo Behrens initially became COO and later CFO of ChemoMetec’s American subsidiary, giving Martin Helbo Behrens direct experience in what has developed into the company’s largest geographical market. During this period, North America became increasingly important to ChemoMetec, and the Board later highlighted that Martin Helbo Behrens had made a significant contribution to the company’s growth and commercial success in the region. This experience is particularly relevant because the United States remains ChemoMetec’s most important market and is home to many of the pharmaceutical and biotechnology companies that represent the company’s core customers. After nearly three years in the United States, Martin Helbo Behrens returned to ChemoMetec’s headquarters in Allerød in 2023 as Deputy COO. Martin Helbo Behrens was promoted to COO in February 2024 and became CEO the following month at the age of 31. The appointment followed the departure of Rasmus Kofoed, who had served as CEO for only a relatively short period. The Board explained that ChemoMetec had reached a phase in its development that required a different combination of executive management capabilities and selected Martin Helbo Behrens from within the organization. The appointment therefore represented a return to an internal leader with extensive operational experience and direct knowledge of ChemoMetec’s most important international market. Since becoming CEO, Martin Helbo Behrens has led ChemoMetec during an important transition in the company’s product portfolio. The established NucleoCounter platform remains central to the business, but ChemoMetec is increasingly positioning the newer XcytoMatic platform around automation and integration into pharmaceutical manufacturing workflows. Martin Helbo Behrens has placed particular emphasis on bioprocessing, where ChemoMetec sees an opportunity to expand beyond its historically strong position in cell and gene therapy and become a larger supplier of analytical equipment used in traditional biopharmaceutical manufacturing. Partnerships have become an important part of this strategy. Rather than attempting to provide every component of an automated pharmaceutical production system itself, ChemoMetec increasingly wants its instruments and software to connect with equipment supplied by other companies. Martin Helbo Behrens has described these partnerships as important to strengthening ChemoMetec’s position in bioprocessing and generating future growth. One example is the collaboration with Roche Diagnostics to connect ChemoMetec’s XM30 with Roche’s Cedex Bio Analyzer. The approach could allow ChemoMetec to participate in larger automated production ecosystems while remaining focused on its core expertise in cell counting and analysis. Software has consequently become a more important strategic priority under Martin Helbo Behrens. ChemoMetec has increased its focus on software development and integration capabilities as the company works to make XcytoMatic instruments part of increasingly automated customer workflows. This includes continued development of the XM Octopus software platform, which enables capabilities such as remote instrument control, centralized data management, fleet management, and integration with other systems through APIs. These capabilities represent an important development for ChemoMetec because the value of its products could increasingly depend not only on the quality of the individual cell counter but also on how easily the instrument can become part of a customer’s wider production environment. Martin Helbo Behrens has also continued to develop ChemoMetec’s commercial organization, particularly in the United States. Given Martin Helbo Behrens’s previous experience running parts of the American organization, this is an area where Martin Helbo Behrens has considerable direct knowledge. ChemoMetec decided to divide the US market into four regions, each with its own regional manager and office, with the objective of bringing the organization closer to customers and improving its understanding of local market conditions. The company is also establishing an office in San Francisco and strengthening its American organization with additional expertise in areas such as integration, software development, and engineering. Another important task under Martin Helbo Behrens is managing the transition between product generations. ChemoMetec decided in 2026 to phase out the NC 200, one of its established instruments, and move customers toward newer products. The NC 203 is intended to provide a relatively natural replacement for many existing customers, while customers seeking greater automation can transition toward XcytoMatic. This is strategically important because ChemoMetec operates in markets where customers may spend considerable time validating equipment before incorporating it into regulated workflows. Replacing an established product therefore requires more than simply persuading customers to purchase a newer instrument. ChemoMetec needs to support customers through the transition while protecting relationships and minimizing disruption to validated processes. Martin Helbo Behrens has acknowledged that replacing the NC 200 with the NC 203 over the coming years will be a significant undertaking requiring dedicated resources. Martin Helbo Behrens’s background is somewhat unusual for the CEO of a specialized life science technology company because Martin Helbo Behrens did not rise through scientific research or product development. Instead, Martin Helbo Behrens has developed through finance, operations, and commercial management inside ChemoMetec. This may be particularly relevant at the company’s current stage of development. ChemoMetec already possesses specialized scientific and technological expertise, while many of the challenges ahead involve commercializing newer products, expanding into bioprocessing, developing partnerships, strengthening the sales organization, and integrating ChemoMetec’s technology into increasingly automated customer workflows. Martin Helbo Behrens is still relatively early in the CEO tenure, making it too soon to determine the long term success of the strategy. Nevertheless, Martin Helbo Behrens brings extensive company specific knowledge despite the relatively young age at the time of appointment. Experience in finance, operations, and the strategically important North American market provides Martin Helbo Behrens with an understanding of several important parts of ChemoMetec’s business. The strategic direction under Martin Helbo Behrens is also becoming increasingly clear, with greater emphasis on bioprocessing, XcytoMatic, software, automation, partnerships, and closer customer relationships. The key test over the coming years will be whether Martin Helbo Behrens can successfully manage the transition from ChemoMetec’s established NucleoCounter business while turning XcytoMatic and bioprocessing into meaningful new growth drivers without weakening the strong profitability that has historically characterized the company.
The Numbers
The first number we will look into is the return on invested capital, also known as ROIC. We want to see a 10-year history, with all numbers exceeding 10% in each year. ChemoMetec comes very close to meeting this requirement, with ROIC below our threshold only in 2017. ROIC increased significantly over the following years and peaked at 50,1% in 2022. It has since declined from these extraordinary levels, reaching 27,5% in 2026. While this is considerably below the peak, an ROIC of 27,5% remains very high and shows that ChemoMetec continues to generate substantial profits relative to the capital invested in the business. One of the main reasons ChemoMetec has historically generated such a high ROIC is the economics of its business model. The company sells highly specialized analytical equipment at very high margins without requiring the large factories, inventories, and physical infrastructure associated with many manufacturing companies. ChemoMetec does manufacture its instruments and consumables itself, but the economic value of these products comes primarily from the company’s technology, software, intellectual property, and specialized knowledge rather than from large amounts of physical capital. This allows ChemoMetec to generate substantial profits from a relatively small invested capital base. ChemoMetec’s high profit margins are particularly important. The company can sell specialized instruments and consumables at attractive margins because customers place considerable value on accuracy, reliability, and consistency. In areas such as cell and gene therapy and bioprocessing, cell counting represents a small part of the overall cost of developing and manufacturing a medicine, but unreliable measurements can create much larger problems. This makes customers less focused on finding the cheapest cell counter and more focused on using equipment they know can provide reliable results. ChemoMetec’s competitive position further supports these economics. Once an instrument has been validated and incorporated into a regulated production process, customers may be reluctant to replace it because changing analytical equipment can require additional validation, documentation, training, and changes to established workflows. ChemoMetec therefore benefits from switching costs that can help retain customers and support attractive pricing. Its traditional NucleoCounter instruments also generate recurring sales of proprietary consumables, meaning an instrument can continue producing revenue long after the original sale. The increase in ROIC leading up to 2022 demonstrates how powerful this business model can be when revenue and profits grow significantly without requiring invested capital to increase at the same rate. ChemoMetec experienced strong growth while margins expanded, allowing earnings to increase much faster than the amount of capital required to operate the business. This combination resulted in the exceptionally high ROIC reached in 2022. The decline in ROIC since 2022 needs some context because it does not necessarily mean that ChemoMetec’s underlying business quality has deteriorated to the same extent. Revenue growth slowed after several years of strong expansion, while profitability also came under pressure for a period. At the same time, ChemoMetec began investing more heavily in its next generation of products, automation, software, production capacity, and organization. This meant that the amount of capital invested in the business increased while the earnings generated from some of those investments had not yet fully materialized. This is particularly relevant for the XcytoMatic platform. ChemoMetec is investing in developing the technology, software, production capabilities, and commercial organization required to establish XcytoMatic in cell and gene therapy and bioprocessing. These investments increase the company’s capital base today, but customers in regulated pharmaceutical manufacturing can require considerable time to validate new equipment before adopting it more broadly. There can therefore be a significant delay between ChemoMetec making an investment and that investment reaching its full earnings potential. ChemoMetec is also becoming a somewhat more investment intensive business. The company continues to invest in product development, software, automation, additional production capacity, and its facilities in Allerød. It is also expanding its commercial organization and developing capabilities that will allow its instruments to become integrated into increasingly automated pharmaceutical manufacturing workflows. These investments are intended to create future growth, but they make it more difficult to maintain the extraordinary ROIC achieved when ChemoMetec was generating rapid earnings growth from a smaller capital base. The development in recent years is nevertheless encouraging. ROIC recovered significantly from its 2024 low and remains at a very high level in 2026 despite the investments being made across the business. At the same time, sales of XcytoMatic have increased considerably, suggesting that some of the investments made in recent years are beginning to contribute more meaningfully to revenue. If this continues, ChemoMetec could eventually generate substantially more earnings from investments that have already been made. Looking ahead, there are good reasons to believe that ChemoMetec can continue generating a high ROIC, although I would not expect the company to consistently return to the extraordinary levels reached around 2022. The fundamental characteristics that have historically supported high returns remain largely intact. ChemoMetec generates high margins, operates in specialized markets with meaningful switching costs, benefits from recurring revenue from its installed base, and does not require enormous amounts of physical capital to grow. The most important question is what returns ChemoMetec can generate from the investments currently being made in XcytoMatic, software, automation, production capacity, and bioprocessing. If XcytoMatic becomes widely validated and integrated into automated pharmaceutical manufacturing, ChemoMetec could generate considerably more revenue and profit from investments that have already been made. This would allow earnings to grow faster than invested capital and could support higher ROIC over time. However, continued investment will also increase the capital base, while long validation cycles mean that returns on these investments may take several years to materialize. ROIC could therefore remain below its historical peak even if ChemoMetec continues to perform very well operationally. This would not necessarily be negative if the company is reinvesting capital at attractive rates and creating a larger business over time.

The next numbers are the book value + dividend. In my old format this was known as the equity growth rate. It was the most important of the four growth rates I used to use in my analyses, which is why I will continue to use it moving forward. As you are used to see the numbers in percentage, I have decided to share both the numbers and the percentage growth year over year. To put it simply, equity is the part of the company that belongs to its shareholders – like the portion of a house you truly own after paying off part of the mortgage. Growing equity over time means the company is becoming more valuable for its owners. So, when we track book value plus dividends, we’re essentially looking at how much value is being built for shareholders year after year. ChemoMetec has delivered a particularly consistent development, with equity increasing every year throughout the period. This is encouraging because it shows that the company has continuously built shareholder value rather than relying on a few particularly strong years to drive the long term development. The most important reason for this consistent growth is ChemoMetec’s profitability. The company has generated substantial profits throughout the period, supported by high margins and a business model that requires relatively little capital compared with the earnings it produces. When ChemoMetec generates a profit, part of that profit can be distributed to shareholders as dividends while the remainder stays within the company and increases retained earnings. Over time, these retained profits accumulate and increase shareholders’ equity. ChemoMetec’s business model makes this particularly powerful. Much of the value behind its products comes from technology, software, intellectual property, and specialized knowledge rather than large amounts of physical capital. The company manufactures its instruments and consumables itself and needs to invest in production facilities and equipment, but these capital requirements have historically been relatively modest compared with the profits generated by the business. This has allowed ChemoMetec to finance much of its growth internally while continuing to build equity. The company’s high margins also play an important role. ChemoMetec operates in a specialized market where customers place considerable value on accurate and consistent measurements. Once its instruments have been validated and incorporated into pharmaceutical workflows, customers can also be reluctant to switch to another supplier. Combined with recurring revenue from consumables and services, this has allowed ChemoMetec to generate substantial earnings and cash flows from its installed base. Another important factor is that ChemoMetec has not needed to rely heavily on debt to finance its growth. Instead, the company has accumulated a strong balance sheet through internally generated cash. ChemoMetec ended 2026 with approximately DKK 725 million in equity and around DKK 290 million in cash. This is particularly encouraging because the company has simultaneously been investing in new products, software, automation, production capacity, and international expansion. The investments being made in recent years could become increasingly important for future equity growth. ChemoMetec is investing in XcytoMatic, the NC 203, software, automation, production capacity, and its expansion into bioprocessing. These investments require capital today, but the objective is to create a larger earnings base in the future. If XcytoMatic becomes more widely adopted and ChemoMetec establishes a stronger position in automated bioprocessing, higher earnings could provide additional profits that can either be reinvested in the company or returned to shareholders. There is also an important connection between the equity development and the ROIC we looked at previously. Growing equity is most valuable when management can continue reinvesting that capital at attractive rates. A company can increase its equity simply by retaining earnings, but that does not necessarily create substantial shareholder value if those retained earnings generate poor returns. ChemoMetec has historically been able to combine increasing equity with a very high ROIC, suggesting that the company has been able to put much of its growing capital base to productive use. Looking ahead, there are good reasons to believe that ChemoMetec can continue growing equity over the longer term, although the growth rate may fluctuate from year to year. The most important factor will be whether the company can maintain its high profitability while successfully investing in its next generation of products. As long as ChemoMetec remains profitable and retains part of those profits within the business, equity should generally continue increasing. The biggest question is therefore not simply whether ChemoMetec can continue growing equity, but whether it can continue earning attractive returns on that growing equity base. Investments in XcytoMatic, software, automation, and bioprocessing are increasing the amount of capital employed in the business. If these investments eventually generate the growth management expects, ChemoMetec should be able to combine further equity growth with high returns on capital. If they fail to generate sufficient earnings, equity could still increase while the returns generated on that capital gradually decline.

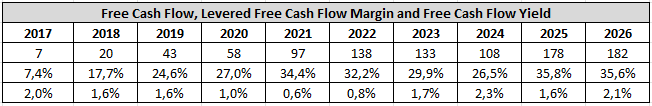
Finally, we will analyze the free cash flow. Free cash flow, in short, refers to the cash that a company generates after covering its operating expenses and capital expenditures. I use levered free cash flow margin because I believe that margins provide a better understanding of the numbers. Free cash flow yield refers to the amount of free cash flow per share that a company is expected to generate in relation to its market value per share. hemoMetec’s free cash flow has developed very strongly over the past decade. While there have been a few years of decline, the overall direction has been clearly upward, and free cash flow reached a record DKK 182 million in 2026. The levered free cash flow margin has also remained very high and reached 35,6% in 2026, meaning that more than one third of revenue was converted into free cash flow. One of the main reasons ChemoMetec generates so much free cash flow is the underlying profitability of the business. The company sells highly specialized cell counting and analysis equipment at high margins, while its installed base generates additional revenue from consumables and services. Once customers have incorporated ChemoMetec’s instruments into their workflows, particularly in regulated areas such as cell and gene therapy, the relationship can continue for many years. This creates an attractive combination of instrument sales and recurring revenue without requiring ChemoMetec to continuously win the same customers again. The business has also historically required relatively little capital compared with the profits it generates. ChemoMetec manufactures its own instruments and consumables and therefore needs production facilities and equipment, but much of the value behind its products comes from technology, software, intellectual property, and specialized knowledge. This means the company can generate substantial earnings without needing to continuously invest enormous amounts in factories, machinery, or inventory. The result has historically been strong conversion of earnings into cash. This helps explain why free cash flow increased significantly as ChemoMetec grew. Revenue increased substantially over the period, while the company was able to spread many of its costs across a larger business. At the same time, high margin consumables and services contributed recurring revenue from the growing installed base. As a result, free cash flow increased from just DKK 7 million in 2017 to DKK 182 million in 2026, while the free cash flow margin expanded considerably. The development has not been completely linear. Free cash flow declined in 2023 and again in 2024 after reaching a then record level in 2022. This coincided with a period of slower growth and increased investments as ChemoMetec began preparing the business for its next phase. The company has been investing in new products, software, automation, production capacity, and its facilities in Allerød. These investments use cash today even though the financial benefits may not appear until several years later. Free cash flow recovered strongly in 2025 and reached another record in 2026 as revenue and profitability increased. The development is particularly encouraging because the record was achieved despite ChemoMetec simultaneously investing heavily in future growth. During 2026, the company made substantial investments in growth initiatives covering areas such as software, automation, product development, and its facilities in Allerød. Generating record free cash flow while making these investments indicates how strongly the underlying business currently generates cash. However, these investments are also why I would be careful about expecting free cash flow to continue setting a new record every year. ChemoMetec expects capital expenditures to increase further in 2027 as the company continues investing in its next phase of growth. This is a substantial amount relative to the size of the company and reflects management’s decision to invest aggressively while it sees attractive opportunities for future growth. These investments are spread across several areas rather than being concentrated in a single project. ChemoMetec is investing in software, automation, product development, facilities, and biological research used to develop protocols and make it easier for customers to adopt and transfer ChemoMetec’s technology into their workflows. Software is expected to represent approximately 20% to 25% of research and development investments going forward, including continued development of the XM Octopus platform. Management’s approach to these investments also appears relatively disciplined. ChemoMetec has indicated that the level of investment will depend on both growth and customer demand. If customers request additional functionality or integration capabilities, the company is willing to invest in developing them when management believes the potential return justifies the spending. This is important because high capital expenditures are not necessarily negative for free cash flow if the money can ultimately be reinvested at attractive rates. The XcytoMatic platform represents one of the most important areas where these investments could eventually support higher free cash flow. ChemoMetec is attempting to move beyond stand alone cell counters and become more deeply integrated into automated pharmaceutical manufacturing workflows. This requires investments in instruments, software, integration capabilities, and customer validation today, but the potential reward is a larger addressable market within bioprocessing and a deeper position within customers’ production processes. There can be a considerable delay before these investments reach their full potential. Pharmaceutical customers operating regulated production processes can take years to validate new analytical equipment. ChemoMetec may therefore spend money developing and commercializing a product well before the customer begins using it at larger scale. This could create periods where capital expenditures increase faster than cash generation even if the long term economics of the investment remain attractive. Looking further ahead, there are good reasons to believe that ChemoMetec can generate more free cash flow over the longer term, although I would not expect it to increase in a straight line. The company continues to benefit from high margins, recurring revenue from its installed base, strong positions within cell and gene therapy, and relatively modest capital requirements compared with the profits generated by the business. If revenue continues growing, these characteristics should support higher operating cash flow. ChemoMetec primarily uses its cash generation to reinvest in the business, maintain a strong balance sheet, and return capital to shareholders. Reinvestment currently includes XcytoMatic, software development, automation, biological research, product development, production capacity, and the expansion of its facilities in Allerød. These investments are intended to strengthen the company’s existing position in cell and gene therapy while building a larger presence in bioprocessing. Returning cash to shareholders is also becoming an important use of ChemoMetec’s cash. In addition to paying dividends, the company has introduced a share buyback program. By the end of fiscal 2026, ChemoMetec had repurchased approximately 105.000 shares for around DKK 39 million, and management subsequently reported that the number had increased to approximately 206.600 shares, corresponding to around 1,2% of the company’s share capital. ChemoMetec can make these investments and return cash to shareholders while still maintaining a strong financial position because of the substantial cash generated by the underlying business. This gives management considerable flexibility when allocating capital. Cash can be directed toward internal growth opportunities when attractive opportunities are available, while excess capital can be returned to shareholders when it is not required by the business. The free cash flow yield suggests that while ChemoMetec is still trading at a premium valuation, it is currently valued more attractively than it has been in most years. However, we will revisit the valuation later in the analysis.
Debt
Another important aspect to consider is debt. I assess whether a business has a manageable level of debt by looking at whether it could be repaid within three years of earnings. In ChemoMetec’s case, the company has no debt. I prefer investing in companies without debt because they have the flexibility to pursue new opportunities quickly without needing creditor approval and are generally better positioned to withstand economic downturns, since they are not weighed down by repayment obligations. ChemoMetec’s debt free balance sheet is particularly noteworthy because the company is currently investing heavily in its next phase of growth. The company made substantial investments in growth initiatives in fiscal 2026, including software, automation, product development, and its facilities in Allerød, while capital expenditures are expected to increase further in fiscal 2027. At the same time, ChemoMetec is paying dividends and repurchasing shares. The company can therefore fund significant investments and return capital to shareholders without relying on debt, which reflects the strong cash generation of the underlying business.
Support the Blog
I want to keep the blog free and accessible for everyone. If you enjoy the content and would like to support it, you can buy me a cup of coffee through PayPal. Every little bit helps and is truly appreciated!

Risks
Macroeconomic factors is a risk for ChemoMetec because demand for the company’s instruments and consumables ultimately depends on the level of research, clinical development, and manufacturing activity among pharmaceutical companies, biotechnology companies, universities, and other research institutions. While cell counting remains necessary for many of these customers, weaker economic conditions can reduce the amount of research being conducted, delay investments in new laboratory equipment, and cause biotechnology companies to reduce or cancel development programs. This can affect both ChemoMetec’s sales of new instruments and the usage of instruments already installed at customers. This risk is particularly relevant because the United States is by far ChemoMetec’s largest market. The US is home to a large biotechnology industry and many of the companies developing cell and gene therapies, but parts of this industry depend heavily on access to external financing. Smaller biotechnology companies can operate for years without generating meaningful revenue because they need to finance research and clinical trials before a medicine potentially reaches the market. Their ability to raise capital therefore has a significant influence on how much they can spend on employees, research programs, laboratory equipment, and clinical development. Higher interest rates can make this environment more difficult. When capital becomes more expensive and investors become less willing to finance unprofitable biotechnology companies, some customers may reduce spending, postpone projects, reduce their workforces, or discontinue drug development programs altogether. ChemoMetec has already experienced the consequences of this dynamic. Management has described visiting biotechnology clusters such as Cambridge and seeing increasing amounts of empty laboratory and office space following layoffs across the industry. Fewer employees conducting research ultimately means fewer samples being analyzed, which reduces the use of ChemoMetec’s instruments and therefore demand for consumables. This is an important characteristic of ChemoMetec’s recurring revenue model. An installed instrument does not automatically guarantee a fixed amount of consumable revenue. Consumable sales depend partly on how actively customers use their instruments. If a biotechnology company reduces the number of experiments it performs, cuts research programs, or lays off scientists, fewer samples need to be analyzed. The customer may continue owning the ChemoMetec instrument, but the instrument is used less frequently and therefore generates less recurring revenue for ChemoMetec. The same dynamic can become more severe when biotechnology companies leave the market entirely. ChemoMetec experienced lower activity among some of its largest US customers during fiscal 2026, while management also noted that some larger players had disappeared from the market. This negatively affected consumable sales in the short term. A prolonged period of weak biotechnology funding could therefore affect ChemoMetec in two ways. Existing customers could use their instruments less frequently, while fewer new biotechnology companies and research programs could reduce future demand for new instruments. Government funding represents another part of the macroeconomic risk. A meaningful amount of life science research in the United States is supported directly or indirectly by public funding, including funding from the National Institutes of Health. Reductions or uncertainty surrounding research funding can therefore affect universities, research institutions, biotechnology companies, and clinical programs. ChemoMetec has observed clinical trials being cancelled in connection with cuts and uncertainty surrounding NIH funding. If fewer research projects and clinical trials are initiated, there are fewer potential customers and fewer samples requiring cell analysis. The US government shutdown in autumn 2025 demonstrated that the risk does not necessarily require a traditional recession. Political uncertainty and interruptions to government activity affected some of ChemoMetec’s customers and contributed to lower activity and sales. Government agencies play an important role in funding research and overseeing the pharmaceutical industry, meaning political disruptions can influence customers even when the broader economy remains relatively healthy. This exposure is especially relevant to cell and gene therapy. Developing these therapies can require substantial amounts of capital over many years, while many companies operating in the field have products that are still in clinical development and therefore generate little or no commercial revenue. During periods when financing is readily available, new companies can be established, clinical programs can expand, laboratories can hire more employees, and customers can invest in additional analytical equipment. When financing conditions deteriorate, the process can reverse quickly. Companies may reduce pipelines, delay clinical trials, lay off employees, or shut down altogether.
Product development is a risk for ChemoMetec because the company’s long term growth depends on its ability to continuously develop new instruments, software, and automation solutions that meet the demanding requirements of pharmaceutical and biotechnology customers. ChemoMetec has built its market position around specialized technology for cell counting and analysis, and maintaining that position requires the company to continue improving its products as customer workflows become increasingly automated and complex. If ChemoMetec fails to develop competitive products or introduces them too slowly, customers could increasingly choose competing technologies instead. This risk has become particularly important because product development plays a central role in ChemoMetec’s current growth strategy. The company is transitioning from its established NucleoCounter products toward a broader XcytoMatic platform that includes the XM30, XM40, NC 203, the upcoming XM50, software such as XM Octopus, and eventually more complete sample management solutions. ChemoMetec is therefore no longer simply developing individual cell counters. The company increasingly wants its instruments, software, and sample management solutions to become integrated parts of automated pharmaceutical development and manufacturing workflows. This makes product development considerably more complex. A traditional cell counter primarily needs to perform its core analytical function accurately and reliably. An automated solution needs to do this while also communicating with other equipment, handling data correctly, working with software platforms, supporting remote control and automation, and fitting into a customer’s wider production process. As ChemoMetec moves further into bioprocessing, its products may also need to integrate with equipment developed by other suppliers. The collaboration with Roche Diagnostics, for example, involves connecting ChemoMetec’s XM30 with Roche’s Cedex Bio Analyzer at both the hardware and software level. This creates opportunities but also increases the number of technical dependencies that need to work correctly. Software therefore represents an increasingly important part of product development. XM Octopus is being developed to provide capabilities such as remote control, centralized data management, fleet management, and integration with other equipment through APIs. This could strengthen ChemoMetec’s position within automated workflows, but software introduces different development challenges from the company’s traditional hardware products. ChemoMetec needs to ensure that hardware, software, data management, and external integrations work reliably together while continuing to develop new functionality as customer requirements evolve. The consequences of technical problems can also be greater in ChemoMetec’s markets than in many ordinary equipment businesses. Its products can be used in regulated pharmaceutical development and manufacturing, where customers require accurate and reproducible results. A product that works well most of the time is not necessarily sufficient. Customers need confidence that measurements are consistent and that the equipment can operate reliably as part of validated processes. Technical problems discovered after launch could therefore slow customer adoption, require additional development work, or damage ChemoMetec’s reputation for reliability. Customer validation adds another challenge. Successfully completing the technical development of a product does not mean that ChemoMetec immediately begins generating substantial revenue from it. Pharmaceutical customers may need to test and validate new equipment before incorporating it into regulated workflows, and this process can take considerable time. A new product can therefore be technically successful while still taking years to reach its full commercial potential. This makes it difficult to know exactly when the investments made in product development will translate into meaningful sales and cash flow. There is also a financial risk associated with product development. ChemoMetec needs to spend money on engineers, software developers, biological research, prototypes, testing, patents, equipment, and facilities before knowing how commercially successful a product will ultimately become. The company is currently investing significant amounts in growth initiatives, with product development, software, and automation representing important areas of spending. If a project is delayed, abandoned, or ultimately generates less revenue than expected, ChemoMetec may fail to earn an attractive return on the capital already invested. There is also a risk that customer requirements change while products are being developed. Automation within bioprocessing is evolving rapidly, and ChemoMetec needs to understand not only what customers require today but what their production environments may look like several years from now. Developing a technically impressive product that does not fit customers’ actual workflows would create limited value. Another risk is that technological development within cell analysis eventually reduces the differentiation of ChemoMetec’s products. ChemoMetec currently benefits from proprietary imaging technology, software, automation capabilities, and extensive experience in cell counting. However, competing analytical technologies continue to improve. Advances in imaging, artificial intelligence, software, and laboratory automation could allow competitors to develop solutions that are easier to use, more automated, cheaper, or capable of performing additional analyses. ChemoMetec therefore cannot rely indefinitely on the competitive advantages of its existing products and needs to continue innovating to maintain its position.
Frequent changes in leadership is a risk for ChemoMetec because the company has experienced unusually high turnover at the top of the organization. Since its IPO in 2007, ChemoMetec has had eight different CEOs, meaning that leadership continuity has been limited for a company whose strategy requires investments and decisions that can take many years to produce results. One of the most recent CEOs remained in the position for only around eight months before leaving the company. Frequent CEO changes do not necessarily mean that the underlying business is poorly managed, but repeated changes increase the risk that strategic priorities, organizational structures, and capital allocation decisions change before previous initiatives have had sufficient time to mature. This is particularly relevant for ChemoMetec because many of its most important strategic initiatives have long time horizons. Developing a new cell counter or automation platform requires research and development, engineering, software development, customer testing, and eventually validation within customer workflows. Even after a product has been launched, pharmaceutical customers may spend considerable time validating it before incorporating it into regulated processes. Investments made by one management team may therefore not generate meaningful revenue until several years later. If senior management changes repeatedly during this period, a new CEO may have different views about which products, technologies, markets, or customer segments deserve the most investment. ChemoMetec is currently going through an especially important strategic transition. The company is expanding beyond its traditional NucleoCounter business and investing significantly in XcytoMatic, software, automation, bioprocessing, and integration with other laboratory equipment. At the same time, established products such as the NC 200 are being replaced by newer generations such as the NC 203. Executing this transition requires consistency because ChemoMetec needs to coordinate product development, commercial investments, customer validation, partnerships, and production capacity over several years. Frequent changes in leadership could make this process more difficult if new executives repeatedly reassess the strategy or change the pace and direction of investment. The risk is not limited to the CEO position. ChemoMetec has also experienced changes in other senior management positions. An example came when CFO Kim Nicolajsen left the company after a relatively short tenure and was replaced by Philip Massie Price. Chairman Niels Thestrup subsequently acknowledged that the recruitment had not been the right match and indicated that the board had wanted to strengthen the company’s operational focus. A single unsuccessful recruitment is not particularly concerning by itself, but combined with ChemoMetec’s history of CEO turnover, it raises a broader question about management continuity and the board’s ability to consistently recruit senior executives who fit the company and remain for the long term. Repeated changes in senior management can also create execution problems below the executive level. A new CEO or CFO may reorganize responsibilities, introduce new reporting structures, change investment priorities, or replace other managers. Employees can consequently spend time adapting to organizational changes rather than executing the existing strategy. This becomes more important as ChemoMetec grows because the organization is becoming more complex. The company is no longer primarily selling relatively stand alone cell counters. It is building software capabilities, developing automated solutions, expanding within bioprocessing, increasing its US organization, and collaborating with other equipment manufacturers. Managing these activities requires coordination across research and development, engineering, sales, service, software, manufacturing, and finance. Frequent leadership changes can also result in a loss of company specific knowledge. ChemoMetec operates in a specialized industry where understanding the technology is only one part of running the business. Management also needs to understand pharmaceutical customers, validation processes, regulatory requirements, development timelines, competitive technologies, and the company's relationships with important customers. An external executive joining ChemoMetec may require considerable time to develop this understanding. If executives leave after relatively short periods, some of the knowledge and relationships accumulated during their tenure leave with them, while their successors must go through another learning period. This is especially important because ChemoMetec remains a relatively small company. At a very large corporation, the departure of one executive may have a limited effect because there are several layers of experienced management beneath that person. In a smaller organization, individual executives can have greater influence over strategy, culture, investment decisions, and customer relationships. The consequences of selecting the wrong person for a senior position can therefore be proportionally larger. Leadership instability can also affect ChemoMetec’s ability to attract and retain employees. The company competes for specialized employees within areas such as engineering, software, biology, sales, and laboratory automation. Employees considering a long term career with ChemoMetec may value clarity about where the company is going and who is leading it. Repeated changes in senior management can create uncertainty about future priorities, organizational responsibilities, and career opportunities. This does not mean that leadership turnover will necessarily lead to employee departures, but prolonged instability could make retaining important talent more difficult.
Reasons to invest
Favorable market trends is a reason to invest in ChemoMetec because the company is positioned within several structural growth areas in the life science industry. Two of the most important are the continued development of cell and gene therapy and the growing production of biologic medicines. Both trends increase the need for reliable cell counting and analysis, which is the area where ChemoMetec has built its expertise. Cell and gene therapy has changed considerably since the first CAR T therapies were approved. What was once largely an experimental field has developed into a commercial industry with dozens of approved therapies and thousands of clinical programs under development. ChemoMetec has highlighted that there are more than 3.000 ongoing cell and gene therapy trials globally, while the number of approved therapies continues to increase. The large difference between the number of approved therapies and the number still being investigated illustrates the potential runway if even a relatively small proportion of today's clinical pipeline eventually reaches the market. This matters to ChemoMetec because cell counting is required throughout much of the development and manufacturing process. Researchers need to determine how many cells are present and whether those cells are viable during early research, clinical development, process development, and eventually commercial production. ChemoMetec can therefore potentially participate throughout the lifecycle of a therapy rather than only at one point in its development. A successful therapy that progresses from an early clinical program to commercial manufacturing can become a considerably larger opportunity as production volumes increase. CAR T therapy is particularly important. The first CAR T therapies were approved by the FDA in 2017 for certain cancers, and the field has subsequently expanded with additional therapies and indications. Some CAR T treatments have also moved earlier in the treatment pathway rather than being reserved exclusively for patients who have exhausted most other options. Moving from later line treatment toward earlier lines can substantially increase the number of eligible patients and therefore the amount of manufacturing required. The opportunity could become considerably larger if cell therapies expand beyond cancer. Researchers are investigating cell and gene therapies across rare diseases and other areas where existing treatments are inadequate. Autoimmune diseases are particularly interesting because CAR T therapies are being investigated as a way of resetting parts of the immune system in patients with severe autoimmune conditions. It remains uncertain how many of these programs will ultimately become commercially successful therapies, but expansion into additional disease areas would increase the potential patient population and create new applications for cell counting technology. ChemoMetec does not need to predict which individual therapy will succeed. The company supplies tools used by researchers and manufacturers across the industry. Many drug candidates will inevitably fail during development, but a growing overall pipeline means more laboratories conducting experiments, more clinical programs, and potentially more therapies progressing toward commercial manufacturing. ChemoMetec can therefore benefit from broader activity across the industry without taking the same binary development risk as the biotechnology companies developing individual drugs. ChemoMetec is already well positioned within this ecosystem. Its customer base stretches from laboratories conducting early research to companies manufacturing commercial therapies. This means that the company can establish relationships with customers relatively early in their development. If ChemoMetec's instruments become incorporated into a customer's standard operating procedures during research or early clinical development, there is an opportunity for the relationship to expand as the customer progresses toward later clinical stages and eventually commercial production. The favorable market trends extend beyond cell and gene therapy. ChemoMetec is increasingly targeting the much broader bioprocessing market, which includes the development and manufacturing of biologic medicines. Customers use living cells to produce biologics and need to monitor those cells throughout the production process. This includes monitoring bioreactors, following the development of cell cultures, optimizing production processes, and ensuring that manufacturing remains within the required parameters. Bioprocessing is attractive because demand is supported by the long term growth of biologic medicines, biosimilars, and advanced therapies. As more biologic drugs are developed and existing drugs are produced at greater scale, manufacturers require analytical equipment throughout their production facilities. Cell counting is one part of this infrastructure. Unlike an early stage research project that may disappear if funding is withdrawn, commercial biopharmaceutical manufacturing can continue for many years once a successful medicine reaches the market. This could gradually change the composition of ChemoMetec's growth. Historically, developments within life science research and particularly cell and gene therapy have been major drivers of the business. Expanding further into bioprocessing gives ChemoMetec access to a larger market and potentially more recurring production activity. Instead of primarily benefiting from the development of new therapies, the company can increasingly participate in the manufacturing of therapies once they become commercial products.
New products and partnerships is a reason to invest in ChemoMetec because the company is in the middle of what could become an important transformation of its product portfolio. For many years, ChemoMetec built its position around stand alone and semi automated cell counters such as the NC 200. The company is now moving customers toward the newer XcytoMatic technology platform, while simultaneously developing products that can become part of much larger automated laboratory and manufacturing systems. If successful, this could allow ChemoMetec to expand from primarily being a supplier of cell counters into a broader provider of cell analysis and sample management solutions for pharmaceutical manufacturing. The first encouraging sign is that ChemoMetec's newer products are beginning to gain commercial traction. Management has spent considerable time validating the XM30, XM40, and NC 203 with customers, and demand increased significantly toward the end of the latest financial year. XcytoMatic had a record year, and the newer products accounted for an increasing share of instrument sales. Management expects XcytoMatic to eventually account for most of ChemoMetec's instrument revenue, making the transition increasingly important to the company's future growth. The NC 203 is an important part of this transition because ChemoMetec has announced that sales of the NC 200 will end in April 2027 after almost 16 years on the market. Thousands of NC 200 instruments have been sold, creating a substantial installed base that customers will eventually need to replace. Some customers are making final purchases of the NC 200 to ensure they can continue using the instrument for several years, while others have already begun validating the NC 203, XM30, or XM40 as replacements. Replacing the NC 200 is not as simple as convincing customers to purchase a newer instrument. Many of ChemoMetec's customers operate in regulated environments where the NC 200 has already been validated as part of an established process. Changing the instrument can therefore require additional documentation and validation. ChemoMetec has attempted to make this transition easier by developing protocols that allow the NC 203, XM30, and XM40 to generate results comparable with those produced by the NC 200. For customers working with CAR T therapies, this can reduce the work required when replacing an existing instrument. The NC 203 is particularly suitable for customers that want to remain with the familiar cassette based workflow rather than moving directly to a fully automated setup. This gives ChemoMetec a relatively straightforward replacement product for customers that have used the NC 200 for many years. At the same time, the replacement cycle creates an opportunity to move some customers further into the XcytoMatic portfolio. Instead of replacing an NC 200 with another stand alone instrument, customers can use the transition as an opportunity to automate parts of their workflows with the XM30. This means that the discontinuation of the NC 200 could become more than an ordinary replacement cycle. ChemoMetec has observed customers evaluating combinations of the NC 203 and XM30 depending on the requirements of different departments. Some customers may continue using a cassette based instrument for certain applications while adopting an automated XM30 elsewhere. If this occurs across a meaningful portion of the installed NC 200 base, the transition could increase ChemoMetec's revenue per customer while also expanding the installed base of its newer technology platform. An important advantage is that the different products have been developed to produce consistent and comparable results. A large pharmaceutical company may use cell counters in research, process development, clinical manufacturing, and commercial production across several facilities and countries. Historically, different departments could use instruments from several manufacturers, making it more difficult to compare results across the organization. ChemoMetec wants customers to use the same underlying technology platform across these different environments, with the NC 203 serving less automated applications and the XM30 and XM40 serving more automated workflows. This creates the possibility that ChemoMetec can become the preferred cell counting platform across an entire pharmaceutical organization rather than supplying individual instruments to individual laboratories. Management has described situations where discussions that initially involved replacing a relatively small number of instruments developed into much larger projects because customers began considering global alignment around a common cell counting platform. These projects take longer to validate, but they can also become substantially more valuable if ChemoMetec is selected across multiple departments and facilities. The opportunity becomes even more interesting when partnerships are included. Customers increasingly want complete automated solutions rather than purchasing individual instruments that operate independently. Instead of trying to develop every component itself, ChemoMetec is partnering with established equipment suppliers so that its cell counting technology can become part of broader automated systems. ChemoMetec has established partnerships with Hamilton and Tecan, which manufacture automated liquid handling systems, as well as Roche Diagnostics. The collaboration with Roche involves integrating ChemoMetec's XM30 with Roche's Cedex Bio Analyzer and subsequently commercializing the combined solution. These partnerships provide ChemoMetec with an additional route to customers. Instead of always selling an XM30 as a separate instrument, ChemoMetec's technology can potentially be included when customers purchase broader automation solutions from its partners. This is particularly interesting because some of these partnerships have been driven by customers asking for ChemoMetec's instruments to be integrated with other systems. If ChemoMetec can establish similar partnerships with more recognized suppliers, its cell counting technology could increasingly become a standard component of automated bioprocessing and cell therapy workflows. ChemoMetec is also developing products that could take the company beyond traditional cell counting. The XM50 and Sample Management System are being designed for fully automated processes, allowing multiple samples to be handled and analyzed with less manual intervention. This could help customers increase production, reduce manual work, and ultimately lower the cost of manufacturing cell based therapies. For ChemoMetec, it could expand the addressable market from simply analyzing cells to also helping customers manage samples through automated workflows.
Recurring revenue is a reason to invest in ChemoMetec because a significant part of the company's business continues generating revenue after an instrument has been sold. Instrument sales expand the installed base, while consumables and services generate revenue from that installed base over many years. This creates an attractive model where selling an instrument is not necessarily the end of the customer relationship, but rather the beginning of a longer revenue stream. Consumables have historically been particularly important to this model. ChemoMetec's cassette based instruments require customers to purchase proprietary disposable cassettes and related consumables when performing cell counts. The more frequently customers use their instruments, the more consumables they require. As a result, ChemoMetec benefits not only from increasing the number of instruments in the market but also from increasing activity among existing customers. A laboratory moving from research into clinical development or eventually commercial production can perform substantially more cell counts, potentially increasing consumable revenue without ChemoMetec needing to sell another instrument. This also means that consumable revenue provides an interesting way to participate in the success of ChemoMetec's customers. If more cell and gene therapies progress through clinical development and eventually reach commercial production, the resulting increase in laboratory and manufacturing activity should increase the use of ChemoMetec's instruments. The company therefore has the potential to benefit both when customers initially purchase equipment and later when successful therapies result in greater instrument utilization. Services provide another recurring revenue stream. ChemoMetec generates revenue from installing, maintaining, testing, and servicing its instruments, and service revenue continued to grow even during a year when consumable sales declined. This part of the business could become increasingly important as ChemoMetec moves toward the more advanced XcytoMatic platform. These instruments are designed to become part of automated and potentially regulated workflows where reliability is critical, making ongoing servicing increasingly important for customers. The new partnerships could expand this opportunity further. ChemoMetec's intention is that even when its instruments are sold as part of a larger solution with a partner, ChemoMetec will continue to own the relationship around servicing its own equipment. This is important because partnerships with companies such as Hamilton, Tecan, and Roche could therefore generate more than an initial instrument sale. Each additional ChemoMetec instrument placed through these partnerships can potentially expand the installed base that generates service and other recurring revenue in subsequent years. Software could eventually add a third recurring element to the business model. ChemoMetec is developing XM Octopus as a software platform for fleet management, automation, remote control, centralized data management, and integration between instruments and other systems. The need for this becomes greater as pharmaceutical companies operate increasingly large and complicated equipment fleets. Management has described customers responsible for thousands of instruments, creating a need to monitor whether equipment is operating correctly, whether servicing is required, and whether data can be accessed centrally rather than manually collected from individual laboratories. XM Octopus is intended to address some of these problems. Customers could monitor instruments centrally, access data remotely, connect equipment through APIs, and potentially simplify quality control and regulatory processes. This becomes particularly valuable as ChemoMetec moves further into automated bioprocessing and cell therapy manufacturing, where hardware increasingly needs to communicate with other equipment and software systems. For ChemoMetec, software could make the economics of each installed instrument more attractive. Instead of primarily generating revenue from the original instrument sale followed by consumables and servicing, the company could potentially add recurring software revenue to the same customer relationship. Management has discussed a model where software licenses could be associated with individual instruments and generate annual fees. This business model is still being developed, and XM Octopus has not yet been commercially launched, so software should currently be viewed as a potential future revenue stream rather than an established part of the investment case. Software could nevertheless become strategically important for another reason. The more of a customer's workflow that depends on ChemoMetec's instruments, consumables, servicing, data, and software, the deeper the relationship becomes. Replacing a cell counter is one decision, but replacing equipment that is connected to fleet management, data systems, automation, and validated manufacturing processes can be considerably more complicated. Successful software adoption could therefore both generate additional recurring revenue and strengthen the switching costs surrounding ChemoMetec's installed base.
Unlock Exclusive Seeking Alpha Discounts – Level Up Your Investing With Zero Risk
If you’ve been thinking about improving your investing process, this is the easiest way to start. These offers are only available through my links, and the Premium plan even comes with a 100% risk-free 7-day trial. Try everything for a week, and if it’s not for you, just cancel. You lose nothing.
1) Seeking Alpha Premium — Try It Free for 7 Days
Access the tools I personally use every day:
• Earnings transcripts
• Stock screeners
• Deep-dive analysis
• Portfolio tracking
• Market news with context that actually matters
Special Price: $269/year (normally $299) + 7-day free trial (for new users only)
Try Premium Free for 7 Days → HERE
(Explore everything — cancel anytime during the trial and pay $0.)
2) Alpha Picks — Proven Stock Ideas
This stock-picking service has delivered +287% returns vs. the S&P 500’s +77% (July 2022–Nov 2025).Great for investors who want curated, long-term picks backed by data.
Special Price: $449/year (normally $499)
Get Alpha Picks → HERE
(Although Alpha Picks doesn’t offer a free trial, its historical outperformance means the subscription can often pay for itself quickly if results persist. For many investors, the potential return far outweighs the upfront cost).
3) Premium + Alpha Picks Bundle — Best Value
Get both services together and save $159.Perfect if you want both broad tools and high-conviction stock ideas.
Special Price: $639/year (normally $798)
Get the Bundle → HERE
(This bundle doesn’t include a free trial, but it gives you both services at a $159 discount. You get Premium’s in-depth research plus Alpha Picks’ high-performing recommendations, making it the most comprehensive option for serious investors.)
Valuation
Now it is time to calculate the share price. I perform three different calculations that I learned at a Phil Town seminar. If you want to make the calculations yourself for this or other stocks, you can do so through the tools page on my website, where you have access to all three calculators for free.
The first is called the Margin of Safety price, which is calculated based on earnings per share (EPS), estimated future EPS growth, and estimated future price-to-earnings ratio (P/E). The minimum acceptable rate of return is 15%. I chose to use an EPS of 11,60, which is from fiscal year 2026. I have selected a projected future EPS growth rate of 15%. Finbox expects EPS to grow by 18,1% a year in the next five years, but 15% is the highest number I use. Additionally, I have selected a projected future P/E ratio of 30, which is twice the growth rate. This decision is based on ChemoMetic's historically higher price-to-earnings (P/E) ratio. Finally, our minimum acceptable rate of return has already been established at 15%. After performing the calculations, we determined the sticker price (also known as fair value or intrinsic value) to be DKK 348,00. We want to have a margin of safety of 50%, so we will divide it by 2. This means that we want to buy ChemoMetic at a price of DKK 174,00 (or lower, obviously) if we use the Margin of Safety price.
The second calculation is known as the Ten Cap price. The rate of return that a company owner (or stockholder) receives on the purchase price of the company essentially represents its return on investment. The minimum annual return should be at least 10%, which I calculate as follows: The operating cash flow last year was 210, and capital expenditures were 28. I attempted to analyze their annual report to calculate the percentage of capital expenditures allocated to maintenance. I couldn't find it, but as a rule of thumb, you can expect that 70% of the capital expenditures will be allocated to maintenance purposes. This means that we will use 20 in our calculations. The tax provision was 56. We have 17,4 outstanding shares. Hence, the calculation will be as follows: (210 – 20 + 56) / 17,4 x 10 = DKK 141,38 in Ten Cap price.
The final calculation is called the Payback Time price. It is a calculation based on the free cash flow per share. With ChemoMetec's Free Cash Flow Per Share at DKK 10,46 and a growth rate of 15%, if you want to recoup your investment in 8 years, the Payback Time price is DKK 165,12.
Conclusion
I believe that ChemoMetec is an intriguing company with an attractive business model. The company has built its moat through specialized technology, integration into customers’ workflows, regulatory validation, strong customer relationships, and the high cost and inconvenience of changing analytical methods once they have become established, while patents and proprietary consumables further strengthen its competitive position. ChemoMetec has consistently generated a high ROIC, reaching 27,5% in 2026 despite substantial investments in new products, software, automation, and production capacity. This reflects the attractive economics of its high margin and relatively capital light business model. ChemoMetec has also demonstrated strong cash generation, with free cash flow reaching a record DKK 182 million and a free cash flow margin of 35,6% in 2026, showing the company’s ability to convert a significant portion of its earnings into cash while continuing to invest in future growth. There are, however, risks to consider. Macroeconomic factors are a risk because weaker biotechnology funding, higher interest rates, and reduced government research spending can cause customers to cut research, delay clinical trials, and postpone instrument purchases, while lower activity can also reduce demand for consumables from instruments already installed. Product development is another risk because ChemoMetec’s long term growth depends on successfully developing increasingly complex instruments, software, and automation solutions that meet the strict requirements of pharmaceutical and biotechnology customers. Development delays, technical problems, lengthy customer validations, or products that fail to gain sufficient adoption could reduce the returns on these investments and allow competitors to gain market share. Frequent changes in leadership are also a risk, as ChemoMetec has had eight CEOs since its IPO in 2007, creating uncertainty around strategic continuity and execution at a time when investments in XcytoMatic, software, automation, and bioprocessing require consistent execution over several years. Despite these risks, there are several reasons to invest in ChemoMetec. Favorable market trends provide long term growth opportunities as the company is positioned to benefit from the continued development of cell and gene therapy and biologic medicines, both of which require reliable cell counting throughout development and manufacturing. New products and partnerships could provide another growth driver as ChemoMetec expands from stand alone cell counters toward a broader platform of automated cell analysis and sample management solutions. The transition to XcytoMatic, combined with partnerships with companies such as Hamilton, Tecan, and Roche Diagnostics, could expand ChemoMetec’s addressable market and make its technology more deeply integrated into pharmaceutical manufacturing workflows. Recurring revenue further strengthens the investment case because each instrument sold can generate additional revenue from consumables and services for many years, while software such as XM Octopus could eventually add another recurring revenue stream and further integrate ChemoMetec into customers’ workflows. Overall, I believe there are many things to like about ChemoMetec, and I would consider buying shares at the intrinsic value or the margin of safety price of DKK 348, as I believe this could provide an attractive starting point for a long term investment.
Follow my investment journey
I hope you enjoyed this analysis. I regularly publish in depth company analyses on InvestSeekers and share updates on the companies I follow.
If you would like to see what I currently invest in, I publicly share my portfolio and any changes I make over time. You can also learn how to follow or copy my portfolio through the investment platform I use.
Stay updated
If you enjoy my company analyses, you can sign up for my free newsletter to receive my latest analyses, investment ideas, and other updates directly in your inbox. Subscribers may also receive selected content before it is published publicly on InvestSeekers. Simply scroll to the bottom of this page and sign up.
Watch on YouTube
If you prefer a faster and more visual way to understand a company, I also publish videos on YouTube covering Nordic companies that receive relatively little coverage in English. Each video provides an understandable overview of the business, financials, risks, reasons to invest, and valuation.
Follow me on X
I also share more frequent investment updates on X, including company news, new analyses, and changes I make to my portfolio.
A cause I support
If you found my analysis valuable and would like to support a good cause, I encourage you to consider making a small donation to ADEPAC. It is a charity I know firsthand, and I have seen the valuable work they do despite having very limited resources.
Even a small donation can make a difference.


Comments